Buying • Selling • August 1, 2026

A Season to buy and sell

Which season to buy or sell depends on when you are ready! Washington’s real estate market follows a distinct seasonal rhythm. If you are planning a move, understanding the “Spring Sprint” versus the “Summer Stroll” is the difference between a high-stress bidding war and a relaxed, successful negotiation. If you miss both of these markets you are still in the running for the “Holiday Sprint.” Just don’t forget your rain boots and Coffee!

Here is the breakdown of why the calendar month matters just as much as the house itself.

The Early Spring “Sprint” (February – Early April)

In the Pacific Northwest, the real estate market “wakes up” much earlier than the flowers. By February, the “New Year, New Home” energy is in full swing. Is this the right season to buy or sell for you?

The Environment:

  • The “First-to-Market” Surge: Buyers who sat out the holidays hit the market with intensity.

  • Multiple Offer Situations: Because inventory is still building from winter lows, demand often outpaces supply. It is common to see multiple offers on well-priced homes during this window.

Pros & Cons:

Fresh Inventory: You get first dibs on the newest homes of the year. | High Competition: You will likely be competing with other “hungry” buyers.

Optimism: Appraisals are often supported by rising spring data. | Pressure: You may have to waive contingencies to win.

Beat the Heat: You close and move before the peak summer temperatures. | Higher Prices: Scarcity often drives sale prices above the listing price.


The Summer “Stroll” (June – September)

As soon as school lets out and the “Big Dark” is replaced by 9:00 PM sunsets, the market undergoes a significant shift. While many assume summer is the busiest time, it is actually the most balanced. Let’s take a look and see if this might be the right season to buy or sell.

The Environment:

  • The “Vacation Effect”: Many buyers pause their search for family trips, weddings, and graduations.

  • Inventory Catch-up: Homes that didn’t sell in the spring “rush” are still active, and summer listings are still trickling in. This creates a higher Months of Supply, giving you more leverage.

Pros & Cons:

Power: Sellers with homes still on the market by July are often motivated to deal. | “Pick-over” Inventory: Some homes may be “stale” listings with underlying issues.

Contingencies are Back: It is much easier to include home inspections and seller credits. | Heat & Logistics: Moving in 90-degree Washington heat can be a challenge.

Better Visibility: You can see how the AC handles the heat and how the yard truly looks. | Dwindling Options: New listings start to slow down as we head into late August.


The “Holiday Hustle” (Late October – Late December)

This sixty-day window is primarily defined by firm deadlines. Specifically, whether it involves a tax year-end or a job relocation starting January 1st, participants in this market are rarely just “browsing.” Consequently, most buyers and sellers active during this time are moving with a clear mission in mind. Does any of this strike a cord with your circumstances? Maybe this might be the season to buy or sell for you. Furthermore, the desire to be “home for the holidays” creates a unique sense of urgency that you won’t find in the spring.

For Buyers: The Gift of Leverage

Historically, anyone listing a home this time of year is motivated and ready to close.

  • The “Motivated Seller” Factor: Anyone listing their home in November or December usually has to sell. They might be relocating for work, settling an estate, or need to close before the tax year resets. This puts you in a position of power.
  • Tax Advantages: Closing before December 31st can provide significant immediate benefits. In 2026, with the One Big Beautiful Bill Act (OBBBA) provisions in full effect, you may be able to deduct mortgage interest, property taxes, and loan points on the tax return you file just a few months later.

  • The “Vibe Check”: Winter is the most honest time to see a house. You’ll know exactly how the furnace sounds, if the gutters actually drain, and how cozy the living room feels when it’s 4:30 PM and dark outside.

For Sellers: The “Serious Only” Crowd

From a seller’s perspective, the weather and timing play a huge factor.

  • Zero “Looky-Loos”: Nobody tours a home in a December rainstorm just for fun. If a buyer is at your door in late fall, they are pre-approved and ready to sign.

  • Stunning Presentation: Pacific Northwest homes look incredibly inviting when decorated for the holidays. Between the twinkling lights and the cozy hearths, your home’s “emotional appeal” is at an all-time high.

  • Inventory Scarcity: While many neighbors wait until the spring to list, your home stands out as one of the few high-quality options available. This can lead to a surprisingly quick and clean sale despite the season.


Spring/Summer vs. Fall/Winter: At a Glance

Season Market Vibe Best For…
Early Spring (Feb-Apr) High Energy / Competitive Variety & Selection (but expect bidding wars)
Summer (Jun-Sept) Relaxed / Balanced Negotiating repairs & choosing with less pressure
Late Fall/Winter (Oct-Dec) Deadline Driven / Strategic Fast closings, serious buyers, and tax benefits

The Bottom Line

In 2026, we are seeing 6.1%–6.3% mortgage rates stabilize. This means the “panic” of 2024 and 2025 is gone. Whether you buy in the busy spring or the relaxed summer, you are entering a “Decision Mode” market rather than a “Reaction Mode” market.

Which Season is Right for You?

  • Choose Early Spring if: You have a very specific “must-have” list and want the absolute widest selection of high-quality homes, and you have the stomach (and the budget) for a fast-paced negotiation.

  • Choose Summer if: You are looking for a “deal,” want more time to make a decision, and want to keep your inspection and financing contingencies firmly in place.

  • Choose Fall/Winter if: You have a deadline, looking to take advantage of the tax incentives or are noticing you need more or less space in your life.

As your specialist, my job is to help you win in April’s heat, negotiate a credit in August’s sun or fight for your timeline in the winter blues.

Not sure what market to take advantage of, or ready to take the plunge, call for a risk free consultation.


Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com

Buying • Selling • June 1, 2026

Summer Home Maintenance Guide

Here is your 2026 Summer Home Maintenance Guide to keep your property cool, safe, and value-packed.

As we move through 2026, the Pacific Northwest summer is no longer just about enjoying the sun—it’s about preparing for higher heat and protecting your home’s equity. With my 12 years of experience in the Seattle Eastside market, I’ve seen how a few simple summer tasks can save homeowners thousands in long-term repairs.


1. The HVAC “Deep Breath”

Our summers are getting hotter, and your AC or heat pump is now an essential asset.

  • Filter Swap: Replace your HVAC filters every 30–60 days during the summer. This improves air quality and prevents the system from “choking” during a heatwave.

  • Clear the Perimeter: Ensure there is at least 2 feet of clearance around your outdoor condenser unit. Remove any overgrown shrubs, grass clippings, or debris that could restrict airflow.

  • The “Test Run”: Don’t wait for the first 90-degree day. Turn your AC on now to ensure it’s actually blowing cold air. If you hear grinding or rattling, call a pro before their summer schedule fills up.

2. Exterior “Curb Appeal” & Protection

The summer sun and spring rains can take a toll on your home’s shell.

  • Deck Health Check: Sprinkle water on your wooden deck. If it beads up, you’re protected. If it sinks in, it’s time to reseal. Check for loose nails or rotting boards—safety first for those summer BBQs!

  • Window & Door Seals: Inspect the caulking and weatherstripping. Sealing gaps now keeps the cool air inside and lowers your energy bills.

  • Gutter Audit: Even after the spring rains, gutters can fill with “pollen sludge” and debris. Clear them out now to ensure summer thunderstorms don’t cause foundation washouts.

3. Smart Summer Landscaping

In 2026, “Water-Smart” is the new gold standard for Pacific Northwest yards.

  • Mulch Generously: Adding 2–3 inches of organic mulch to your garden beds acts as insulation, keeping the soil cool and moisture locked in.

  • Water Strategically: Water in the early morning or late evening to minimize evaporation. Aim for deep, infrequent soaking rather than daily “spritzing” to encourage deep root growth.

  • The “Defensible Space”: If you live near wooded areas (like Issaquah or Duvall), trim back dead branches and clear dry brush at least 10 feet away from your home to reduce fire risk.

4. Internal Safety Audit

  • Smoke & CO Detectors: Summer is the perfect time to test all alarms and swap out batteries.

  • Ceiling Fan Pivot: Switch your ceiling fans to run counter-clockwise. This pushes cool air straight down, creating a wind-chill effect that allows you to raise your thermostat by a few degrees.

  • Dryer Vent Cleaning: Built-up lint is a leading cause of house fires. Disconnect the vent and vacuum it out to keep your dryer running efficiently and safely.


The Specialist Perspective: Why Maintenance Matters for 2026 Value

In the current more Neutral market During these months, buyers are becoming more selective. When I represent a seller, a home that has a documented history of seasonal maintenance—clean HVAC records, a well-sealed exterior, and healthy landscaping—always commands a higher price and shorter closing time.

If you’re planning to buy or sell this summer, don’t forget Compliance and maintenance go hand-in-hand to protect your home’s legacy.

Contact me today to get started

Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com

Visiting the Pacific Northwest • May 1, 2026

Eastside Summer Guide: The Best of Bellevue, Kirkland, and Beyond

What’s happening on the Eastside for the summer?

1. Life on the Water: Lake Washington & Lake Sammamish

Eastside Summers revolves around the lakes. As the weather warms up in May, the waterfront becomes the community’s living room.
Eastside Summer Guide

Juanita Beach Paddleboarding

  • Kirkland Waterfront: Marina Park is the place to be. You can rent a powerboat or electric boat for a sunset cruise, or simply grab a gelato and walk the promenade. Juanita Beach has a playground, Paddle boarding and kayak rentals and the best Sandy Beach to lounge during our warmer days.

  • Enatai Beach Park (Bellevue): This is a hidden gem for kayakers. You can rent a paddle board and glide through the Mercer Slough Nature Park, where you’ll feel miles away from the city in a lush, wildlife-rich wetland.

  • Lake Sammamish State Park: Ideal for a full day out. With two expansive swimming beaches (Tibbetts and Sunset) and a massive new playground, it’s the premier spot for a summer BBQ.

2. Festival Season: Art, Wine, and Music

The Eastside knows how to throw a summer party. Mark these on your 2026 calendar:

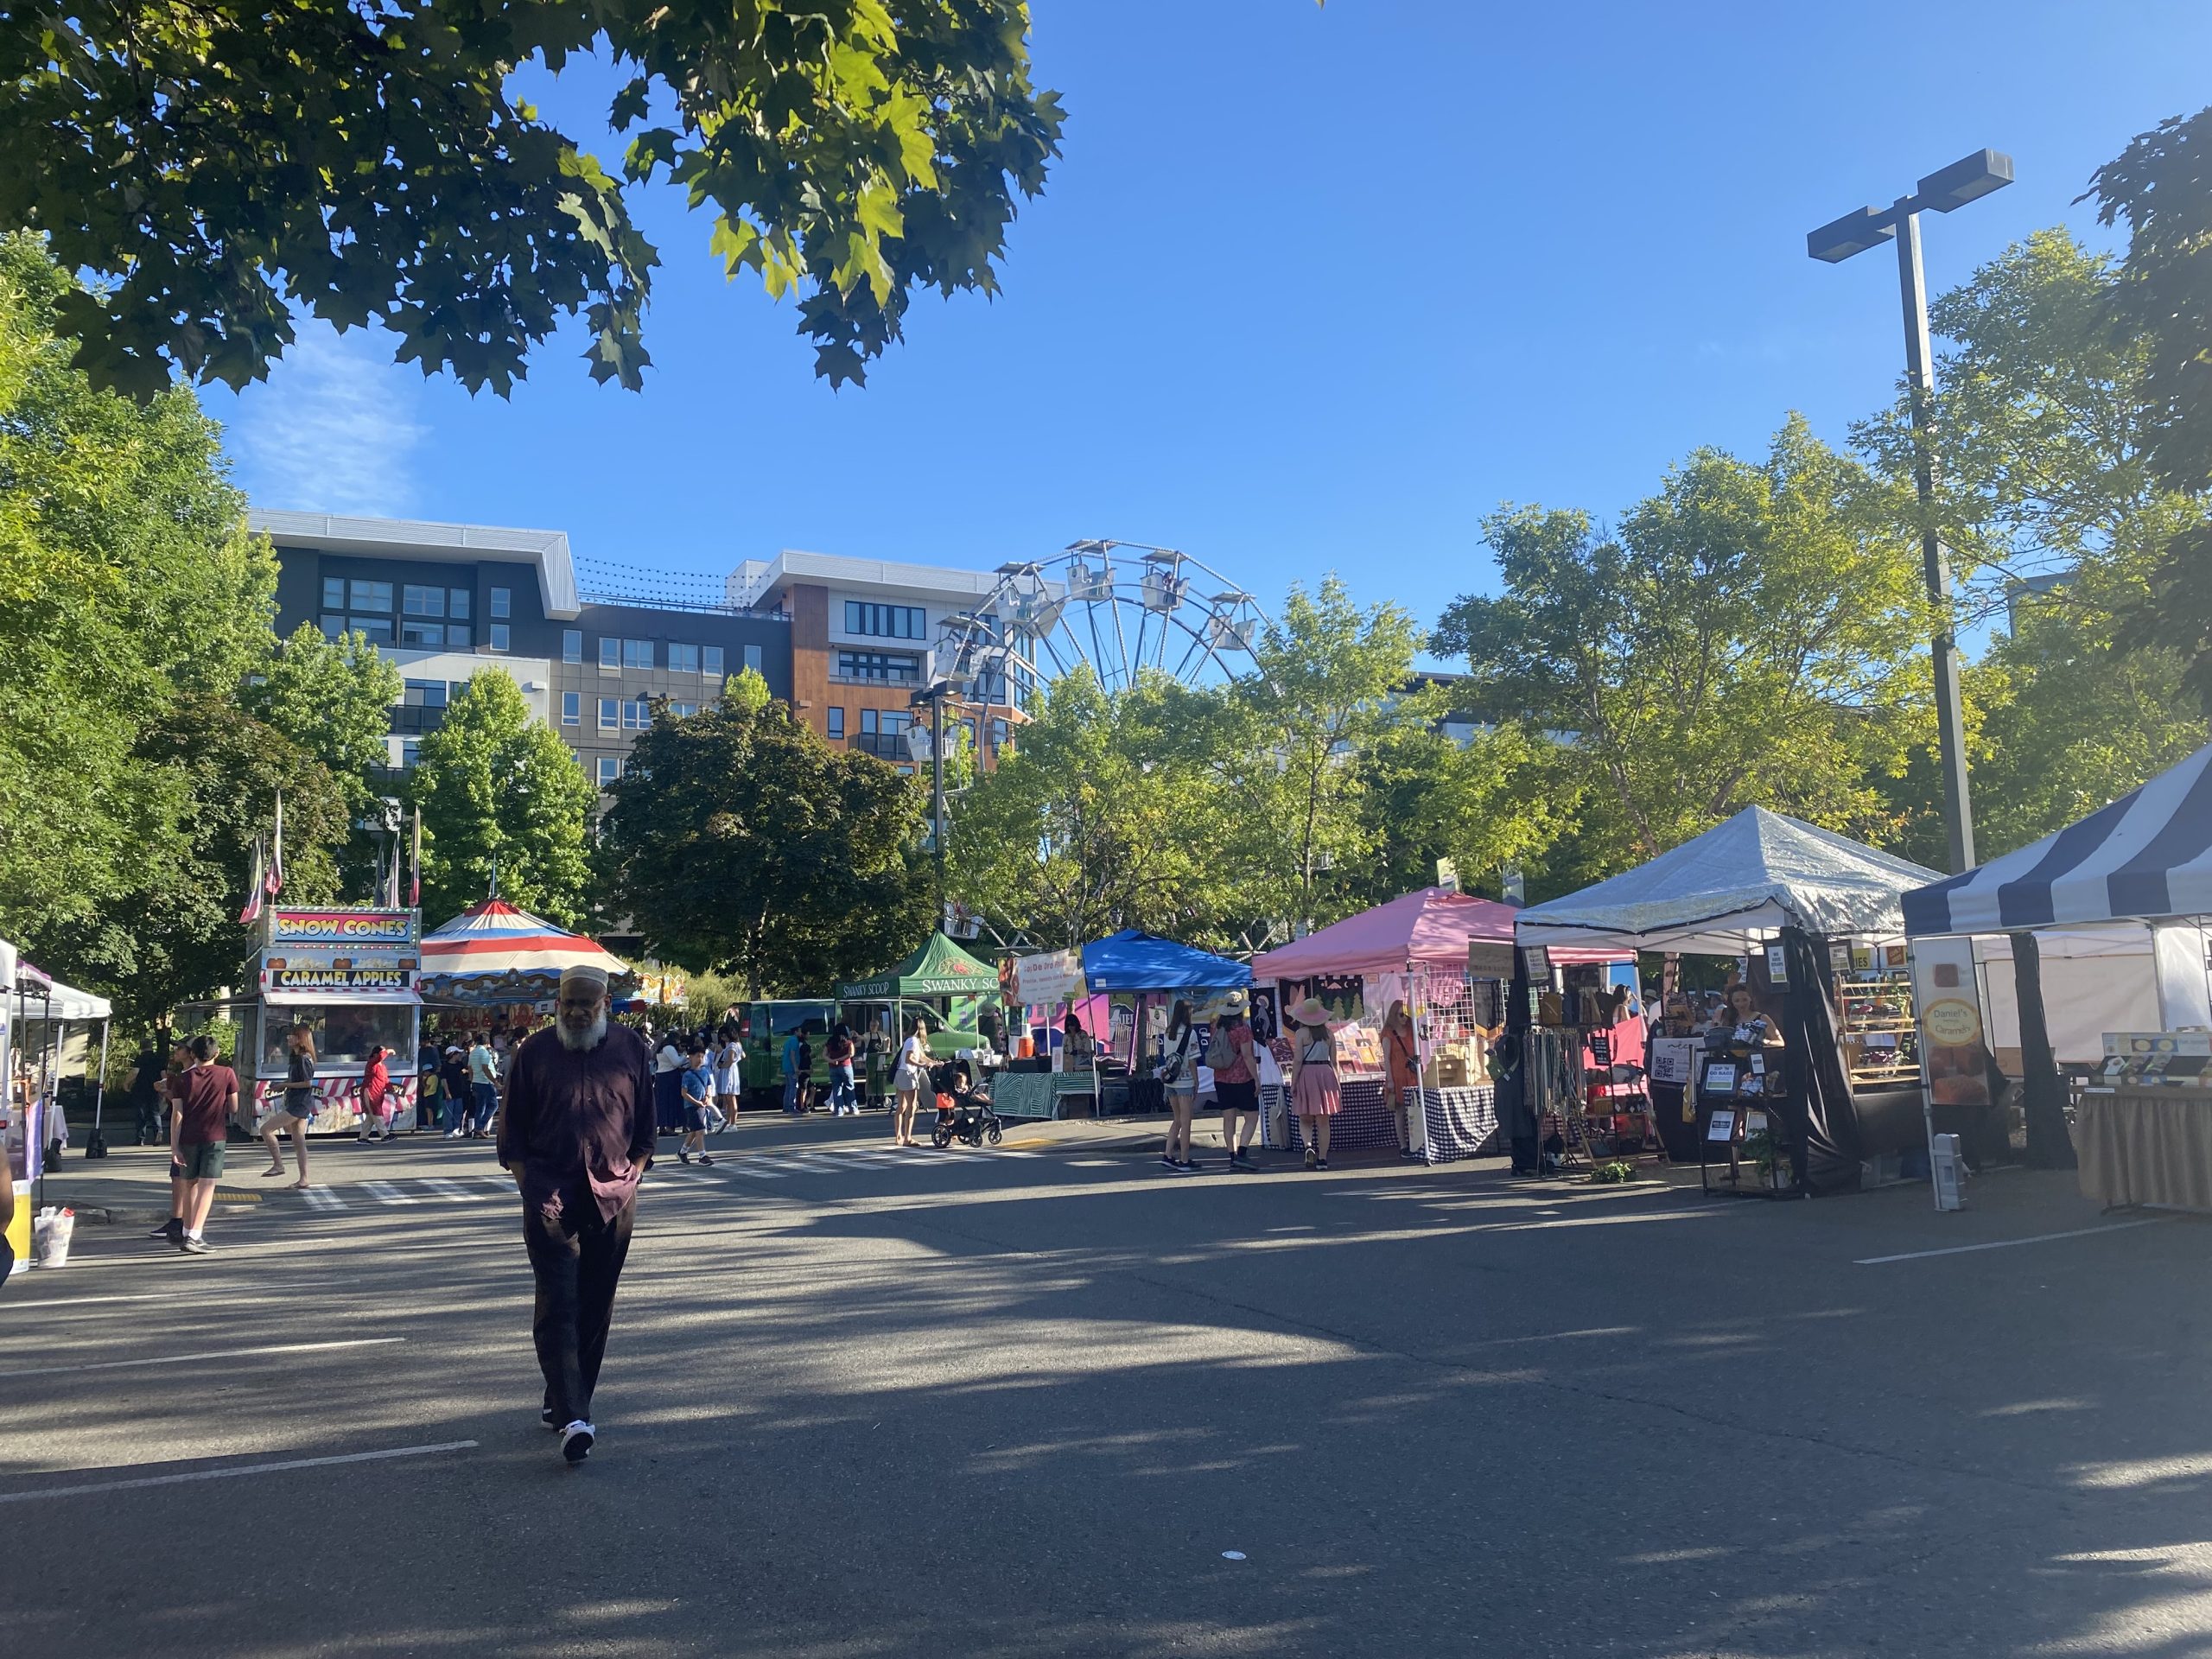
  • Redmond Urban Market

    Bellevue Arts Museum (BAM) ARTSfair (July): One of the largest and most prestigious open-air arts festivals in the Northwest. Over 300 artists take over the streets around Bellevue Square.

  • Kirkland Uncorked (July): A waterfront wine festival at Marina Park featuring Washington’s best vintages, food trucks, and a “Bark-testant” dog show.

  • Sammamish Commons Concerts: Pack a picnic and a blanket for free outdoor concerts on the hill—one of the best views of the sunset on the Eastside.
3. Farm-to-Table & Al Fresco Dining

The Eastside’s culinary scene shines when the patios open up.
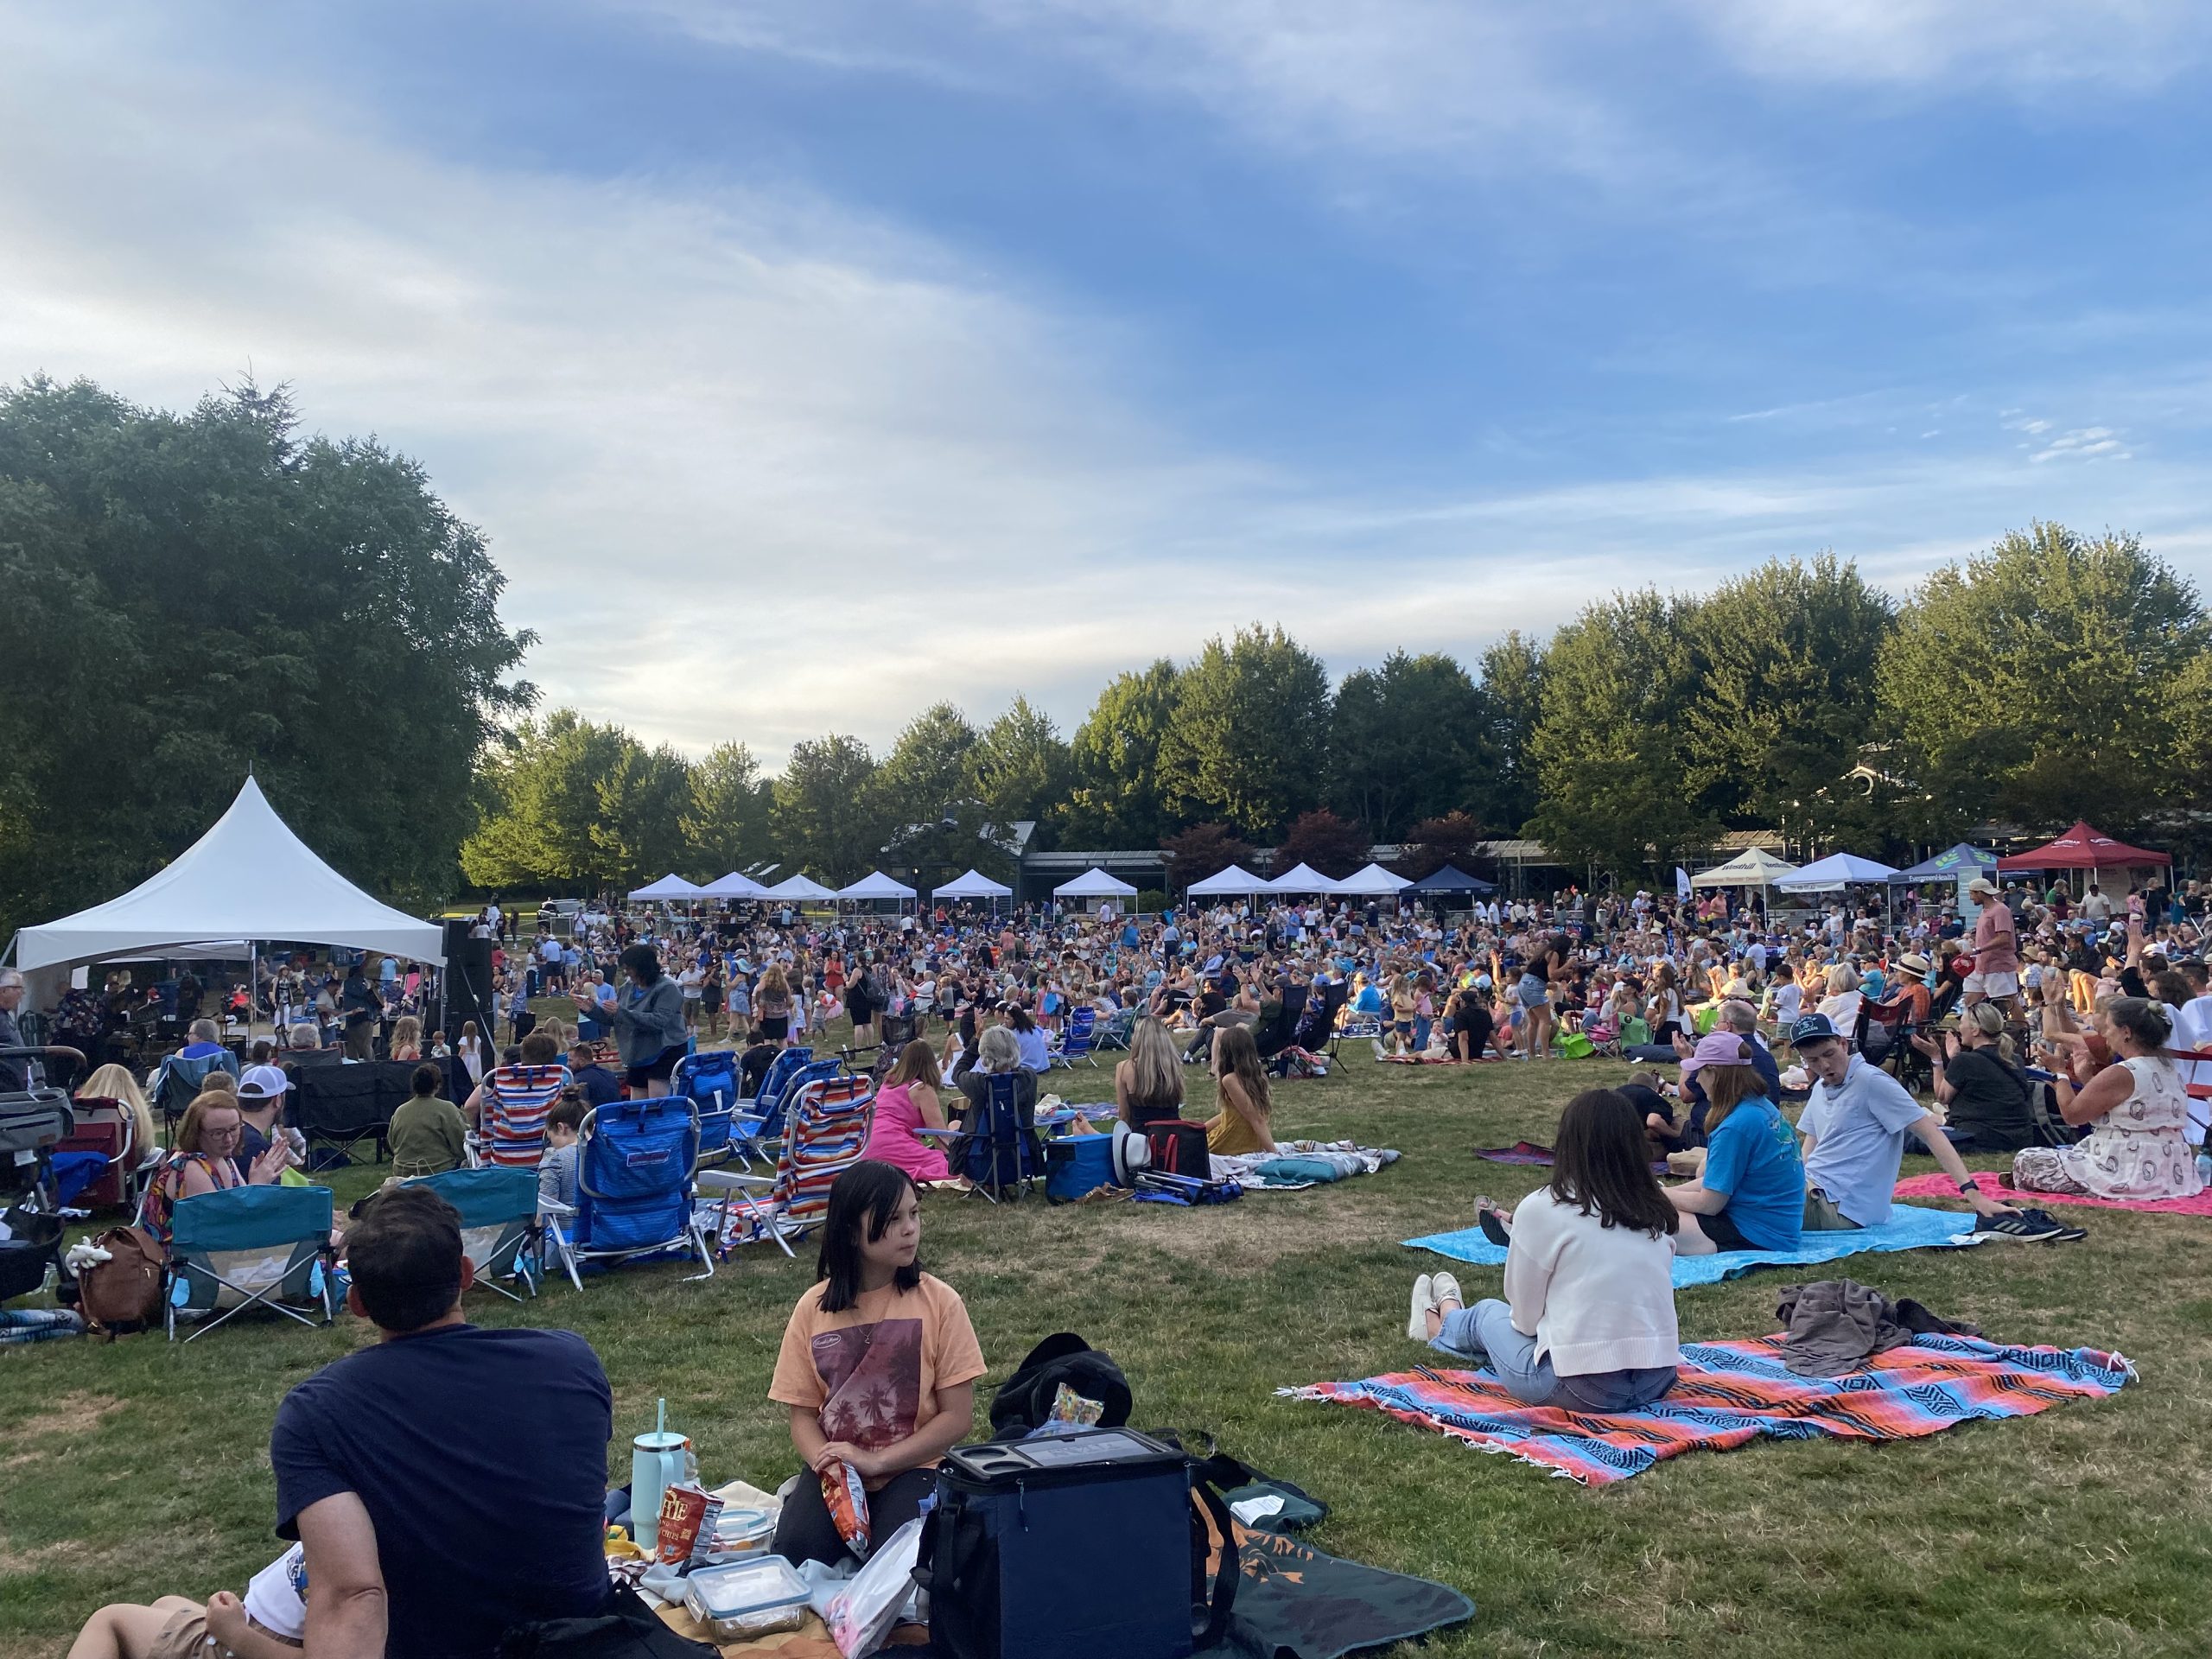
Wilmot Gateway Park, Woodinville

  • Woodinville Wine Country: Just north of Kirkland and 5 minutes off of 405, Woodinville is home to over 130 wineries. In the summer, the lawns at Chateau Ste. Michelle host world-class outdoor concerts. You can also walk along wine alley and stop at boutique shops and restaurants. Bring the whole family to their Summer Concert Series at the slough. Enjoy food, drinks, games and lots of good music each week in July.

  • The Farmers Markets: * Bellevue (Thursdays): Great for a post-work organic haul.

    • Kirkland Wednesday Market: Located right on the water at Marina Park.

  • Remlinger Farms (Carnation): A short drive east, this is a summer rite of passage for families. U-pick berries, a steam train, and a farm-themed fun park.

4. Hiking & The Great Outdoors

You don’t have to drive to the Cascades for a great hike.

  • Cougar Mountain Regional Wildland Park: Over 35 miles of trails right in Bellevue/Issaquah. In the summer, the shade of the forest canopy keeps these trails perfectly cool.

  • Bridle Trails State Park: A 482-acre oasis of old-growth forest between Kirkland and Bellevue, perfect for a peaceful walk or horseback riding.


Why Summer is the Best Time to Explore Your New Neighborhood

If you are considering buying a home on the Eastside, there is no better time than the summer to “test drive” the lifestyle.
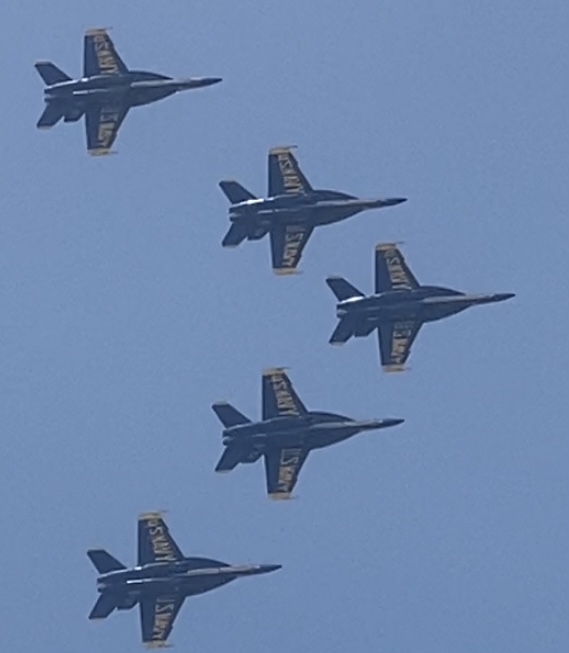
Blue Angles

  • See the “Real” Neighborhood: Walk the streets in the evening to see how active the parks are and how the community interacts.

  • Evaluate the Amenities: Visit the local pools, tennis courts, and HOA-managed beaches while they are in full use.

  • The Specialist Edge: As an Eastside resident and local agent of over 12 years, I don’t just know the houses; I know which streets have the best 4th of July block parties and which buildings have the best rooftop views for the Seafair Blue Angels (or join me to view the Blue angles in person at the Museum of Flight in Renton).

Thinking of buying or selling this summer? Reach out today so I can help you start planning your next move.

Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com

Buying • April 1, 2026

Summer might be the best time to buy!

The “Summer Divergence”: Why Buyers Slow Down While Choice Stays High

When we start out, one thing we think about is: When is the best time to buy a house in King & Snohomish County? When looking at the actual market data, we see a fascinating trend: while the “frenzy” of buyers often cools down late-spring, the number of homes available for you to choose from remains remarkably steady. This is what I call the Summer Opportunity Gap.

1. The Supply Stays, but the “Sold” Sprints Slow Down

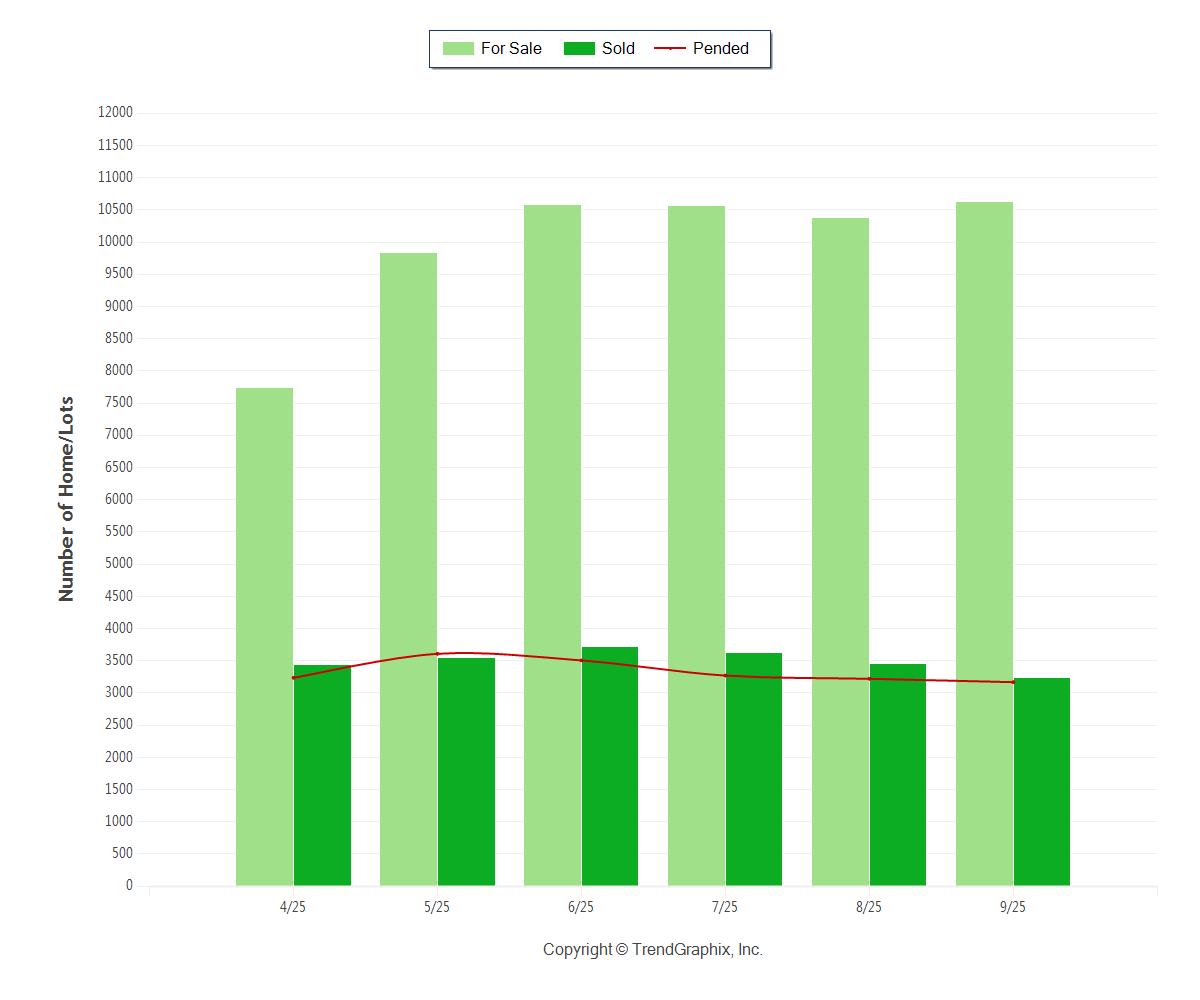
According to the latest TrendGraphix metrics, we are seeing a significant 33.2% drop in Sold properties month-over-month as we move out of the initial spring rush. However, the For Sale inventory is actually increasing by 4.2%. So, When is the best time to buy a house in King & Snohomish County?

  • The Interpretation: The “For Sale” line (the options you have) is climbing, while the “Sold” line (your competition taking homes off the market) is dipping. For the first time in months, supply is outpacing the immediate demand.

2. Moving from a “Seller’s Sprint” to a “Neutral Market”

The report officially classifies the current market as “Neutral.” This is a huge shift from the “Seller’s Market” of previous years.

  • The Benefit to You: In a neutral market, you have Time. You aren’t forced to waive inspections or make a decision in 4 hours. With more “For Sale” inventory staying on the market longer, you have the leverage to negotiate.

3. The “Pended” Reality Check

While “Pending” sales (homes going under contract) show a seasonal uptick of 46% as buyers re-enter the market in spring, they are still down 20.1% from six months ago. * What this means: There is a “ceiling” on the competition. Even though more people are looking than in the dead of winter, the overall volume of competing buyers is significantly lower than the historical peaks.

I‘ve seen this cycle repeat itself for over a decade. The ‘smart money’ moves when the Sold line dips but the Inventory line stays green. That is exactly what we see during the summer months (April to August). If you find yourself asking, When is the best time to buy? and your not looking to be in a rush and not have to deal with multiple offers on a property, this might be the best time for you to start.

Call me today to set you up for success!

Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com

Buying • March 3, 2026

Certified Condo Specialists: Avoid WUCIOA Liabilities
Why You Need a Certified Condo Specialist in 2026

Buying into a Common Interest Community (CIC) in 2026 is an exciting milestone. However, the legal fine print has never been more complex. While Washington state is moving toward a unified law called WUCIOA, many older buildings are currently “out of compliance.” Specifically, several associations have struggled to meet the new mandates that went into effect on January 1st. Which is where you need to make sure your agent is a Certified Condo Specialist, not just a local agent or what some call themselves “condo specialist.” Don’t take an agent’s word for it, ask them for their certification. If they don’t have the above image on any of their business cards or paperwork or the letters CCS after their name, then you will know that they have not been certified by the Council of Condominium Specialists® and the Council of CID Specialists®.

The “Hidden” Special Assessment Risk

Furthermore, WUCIOA now requires much stricter financial transparency. This includes new rules for how reserve funds are held and invested. Consequently, if you buy into a building with an outdated Reserve Study, you face a major risk. You might be walking into a massive Special Assessment that the current owners haven’t disclosed. Therefore, auditing the building’s financial health is no longer optional; it is essential and a Certified Condo Specialist knows how to help you read through the reports.

Your New 2026 Rights

In addition to financial shifts, your personal rights as a homeowner have expanded. Did you know that as a buyer in 2026, you have a statutory right to install an EV Charger or a Heat Pump? Under the new law, a Board cannot “unreasonably” deny these requests. Nevertheless, many buildings still have “blanket bans” in their old bylaws. Since these rules are often unenforceable relics, you need an agent who can spot the difference. Simply put, you need a Certified Condo Specialist (CCS).

The CCS Advantage for Buyers

While most agents focus on the kitchen, I focus on RCW 64.90 compliance. As your specialist, I decode the “Resale Certificate” to find hidden red flags. For example, I look for these key indicators:

  • Are the reserves held in a proper interest-bearing account?

  • Has the Board followed the 2026 open-meeting notice requirements?

  • Is there a clear 24-month repayment plan for any borrowed funds?

Ultimately, my goal is to protect you from a legal headache. I ensure your new home is a sound investment in this new era of real estate.

2026 questions for reviewing HOA Docs


Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com

Buying • December 20, 2024

Debunking common mortgage myths

“Debunking Mortgage Myths: What Every Homebuyer Needs to Know”

The mortgage process can seem overwhelming, especially with the abundance of myths and misconceptions circulating about home loans. Many prospective homebuyers delay or avoid purchasing a home because they believe they don’t qualify or misunderstand how the process works. In this blog, we’ll debunk the most common mortgage myths, separating fact from fiction, so you can approach homeownership with confidence and clarity.

8 Common Mortgate Myths:

Myth #1: You Need a 20% Down Payment to Buy a Home

The Truth: While putting down 20% can help you avoid private mortgage insurance (PMI) and reduce monthly payments, it’s not a requirement.

  • Low-Down-Payment Options: Many loan programs allow for smaller down payments:
    • FHA Loans: As low as 3.5% for qualified buyers.
    • Conventional Loans: Some require as little as 3%.
    • VA and USDA Loans: Offer zero-down-payment options for eligible borrowers.

Why It Matters: Waiting to save for a 20% down payment could delay your homeownership goals unnecessarily. Work with a lender to explore options that suit your financial situation.


Myth #2: You Must Have Perfect Credit to Get a Mortgage

The Truth: While a higher credit score can help you secure better rates, you don’t need a perfect credit score to qualify for a mortgage.

  • FHA Loans: Accept credit scores as low as 500 (with a 10% down payment) or 580 (with a 3.5% down payment).
  • Conventional Loans: Often require a minimum credit score of 620.
  • VA Loans: Typically have flexible credit score requirements.

Why It Matters: Lenders look at the full picture, including your income, employment history, and debt-to-income ratio. A less-than-perfect score doesn’t automatically disqualify you.


Myth #3: You Can’t Get a Mortgage with Existing Debt

The Truth: Having existing debt, such as student loans or car payments, doesn’t mean you can’t qualify for a mortgage.

  • Debt-to-Income Ratio (DTI): Lenders evaluate your ability to manage payments by calculating your DTI. Most prefer a DTI below 43%, but some programs allow higher ratios.
  • Strategies for Approval: Pay down high-interest debts or increase your income to improve your DTI ratio.

Why It Matters: Many buyers are managing student loans or other debts. The key is finding a balance between your debt obligations and monthly mortgage payment.


Myth #4: Pre-Approval Guarantees a Loan

The Truth: Pre-approval is an important step in the homebuying process, but it’s not a guarantee of final loan approval.

  • What Pre-Approval Means: Lenders review your financial information to estimate how much you can borrow.
  • Final Approval Process: The loan is fully approved after underwriting, which includes verifying your finances, property appraisal, and other factors.

Why It Matters: Avoid making large purchases or financial changes after pre-approval to ensure your loan application stays on track.


Myth #5: You Should Always Choose the Lowest Interest Rate

The Truth: While a low interest rate is attractive, it’s not the only factor to consider when choosing a loan.

  • Other Costs to Evaluate:
    • Closing costs and lender fees.
    • Loan terms (e.g., 15-year vs. 30-year).
    • Discount points (fees to lower your rate).
  • Finding the Right Loan: Sometimes a slightly higher rate with lower fees can be a better overall deal.

Why It Matters: Work with your lender to compare the full cost of different loan options, not just the interest rate.


Myth #6: The Mortgage Process Is Too Complicated

The Truth: The mortgage process can seem daunting, but working with the right lender simplifies the journey.

  • What to Expect:
    • Pre-approval to determine your borrowing power.
    • Finding the right loan program for your needs.
    • Underwriting to finalize the loan.
  • How to Stay Organized: Use a checklist to track required documents and deadlines.

Why It Matters: A knowledgeable lender provides guidance at every step, making the process smoother and less intimidating.


Myth #7: You Can’t Qualify Without a Long Employment History

The Truth: While employment stability is important, you don’t necessarily need a long work history.

  • Lender Requirements: Most lenders look for at least two years of consistent employment, but there are exceptions.
  • Special Cases:
    • Recent graduates with job offers.
    • Self-employed individuals with steady income.

Why It Matters: Lenders understand life circumstances vary. Be transparent and provide documentation to show income stability.


Myth #8: It’s Always Better to Rent Than to Buy

The Truth: Renting can be a better choice for some, but buying often provides long-term financial benefits.

  • Building Equity: Mortgage payments contribute to your equity, unlike rent, which builds no ownership.
  • Tax Benefits: Homeownership may provide tax deductions for mortgage interest and property taxes.
  • Fixed Costs: With a fixed-rate mortgage, your monthly payment remains stable, unlike fluctuating rents.

Why It Matters: Evaluate your financial goals and long-term plans to decide if buying is right for you.


Final Thoughts: Empowering Buyers with Accurate Information

Buying a home is a major decision, and misinformation can cause unnecessary stress or delays. By debunking these common mortgage myths, you can approach the process with confidence, armed with the facts needed to make informed choices.

Talk to a lender today:

Tami Bill @ Future First Mortgage


Alicia Ewbank

(206)446-1952

aliciae@windermere.com

aliciaewbank.withwre.com

Buying • December 13, 2024

What Documents Do You Need for a Mortgage?

When you’re ready to buy a home, one of the first steps in securing a mortgage is gathering the necessary documents. Lenders require these to assess your financial health and determine your eligibility for a loan. Being prepared not only speeds up the process but also makes a strong impression on lenders.

So, what documents do you need to be approved for a mortgage?

Lenders use documentation to verify:

  1. Income Stability: To ensure you can afford your monthly payments.
  2. Creditworthiness: To assess your ability and willingness to repay debt.
  3. Assets: To confirm you have enough savings for a down payment and closing costs.
  4. Debts: To calculate your debt-to-income (DTI) ratio and gauge your financial obligations.

This thorough evaluation minimizes risk for the lender while helping you secure the right loan terms.


The Essential Documents You’ll Need

Here’s a checklist broken down into key categories:

1. Proof of Income

  • Pay Stubs: Most lenders require at least two months of recent pay stubs to verify your current income.
  • W-2 Forms: These provide a record of your annual earnings and tax withholdings. Expect to provide forms from the past two years.
  • Tax Returns: If you’re self-employed, a freelancer, or own a business, lenders will ask for two years of tax returns to confirm your income.
  • Profit and Loss Statements: Self-employed buyers may need to supply year-to-date profit and loss statements.

2. Employment Verification

  • Lenders often contact your employer to verify your job status and income stability. Be prepared to provide your employer’s contact information.

3. Proof of Assets

  • Bank Statements: Provide statements from the past two to three months for checking, savings, and investment accounts. Lenders check for sufficient funds for a down payment, closing costs, and reserves.
  • Retirement Account Statements: If you plan to use funds from a 401(k) or IRA, include the latest statement.

4. Credit Information

  • Credit Report Authorization: Lenders will pull your credit report to assess your credit score and payment history. Be ready to explain any issues, such as late payments or accounts in collections.

5. Debt Information

  • Loan Statements: Include details of outstanding loans (e.g., car loans, student loans).
  • Credit Card Statements: Lenders need to know your monthly minimum payments to calculate your DTI ratio.

6. Identification

  • Government-Issued Photo ID: A valid driver’s license or passport is required to confirm your identity.
  • Social Security Number: This is used for credit checks and verifying employment and income.

7. Additional Documents for Special Cases

  • Gift Letter: If someone is gifting you money for your down payment, the lender may require a formal letter stating the funds are a gift and not a loan.
  • Divorce Decree: If applicable, provide a copy to clarify financial obligations, such as alimony or child support.
  • Bankruptcy Discharge Papers: If you’ve filed for bankruptcy in the past, lenders need documentation showing it has been resolved.
  • Rental History: Renters may need proof of consistent rent payments, typically through canceled checks or a letter from the landlord.

Tips for Staying Organized

  1. Create a Digital Folder: Scan all documents and store them in a secure, cloud-based folder for easy sharing with your lender.
  2. Label Files Clearly: Use clear naming conventions (e.g., “Pay Stub_Sept2024.pdf”) to avoid confusion.
  3. Double-Check for Accuracy: Ensure all names, addresses, and financial figures match across documents.
  4. Keep Updated Copies: If your loan process extends beyond a few months, lenders may request updated statements or pay stubs.

Common Pitfalls to Avoid

  1. Inconsistent Information: Mismatched details between your application and documents can delay approval.
  2. Large Cash Deposits: Lenders scrutinize significant, unexplained deposits. Be prepared to document the source of any large sums.
  3. Missing Deadlines: Failing to provide requested documents promptly can prolong the process.
  4. Omitting Debts: Full transparency is essential. Hiding debts can lead to rejection or delays.

Why Staying Prepared Matters

Having your documents ready benefits you in several ways:

  • Speeds Up Approval: A well-prepared application reduces back-and-forth with the lender.
  • Increases Your Credibility: Lenders see you as a reliable borrower.
  • Reduces Stress: Staying organized prevents last-minute scrambling.

What Happens After Submitting Your Documents?

  1. Loan Underwriting: The lender reviews your application and supporting documents.
  2. Conditional Approval: You may receive approval contingent on additional verification.
  3. Final Approval: Once all conditions are met, your loan is finalized, and you’re ready to shop and close on your home.

Final Thoughts: Your Documentation Checklist is Your First Step to Homeownership

Gathering the right documents may seem tedious, but it’s a critical step in securing a mortgage. The effort you put into preparing will save time, reduce stress, and help you move one step closer to owning your dream home.


Talk to a lender:

Tami Bill @ Future First Mortgage


Alicia Ewbank, CCS
Windermere Real Estate East, Inc,
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com

Buying • December 6, 2024

Securing Interest rates and what they are

How to Secure the Best Interest Rate

Securing a favorable interest rate is one of the most important steps in the homebuying process. A lower interest rate can save you thousands of dollars over the life of your mortgage, making homeownership more affordable and manageable. With market conditions constantly changing, knowing how to lock in the best rate can give you a financial advantage.


Understanding How Interest Rates Work

Before diving into strategies, it’s crucial to understand how mortgage interest rates are determined.

Key Factors That Affect Your Interest Rate:

  1. Your Credit Score: Lenders use your credit score as an indicator of financial responsibility. A higher score typically qualifies you for lower rates.
  2. Loan Type: Different loans (e.g., conventional, FHA, VA) have varying rate structures.
  3. Loan Term: Shorter loan terms (e.g., 15 years) generally come with lower rates compared to longer terms (e.g., 30 years).
  4. Market Conditions: Economic trends, such as inflation, Federal Reserve policies, and demand for housing, influence rates.
  5. Down Payment: A larger down payment often results in a better rate because it reduces the lender’s risk.

Tips for Securing the Best Interest Rate

  1. Improve Your Credit Score Before Applying
    • Check Your Credit Report: Request a free credit report from annualcreditreport.com and review it for errors or inaccuracies.
    • Pay Down Debt: Reduce outstanding credit card balances to improve your debt-to-credit ratio.
    • Avoid New Debt: Refrain from opening new credit accounts in the months leading up to your mortgage application.
    • Make Payments on Time: Consistent, timely payments demonstrate financial responsibility.
  2. Compare Lenders
    Not all lenders offer the same rates, so shopping around is essential.

    • Request Rate Quotes: Gather quotes from at least three to five lenders.
    • Understand the Fine Print: Look beyond the interest rate; compare loan terms, fees, and closing costs.
    • Consider Local Lenders: Smaller institutions or credit unions may offer competitive rates or programs tailored to your needs.
  3. Time Your Application Strategically
    • Lock in Your Rate: Once you find a favorable rate, lock it in to protect against market fluctuations. Most locks last 30-60 days, but confirm with your lender.
    • Monitor Market Trends: Work with your lender or Realtor to keep tabs on market changes. Rates can shift daily, so timing matters.
  4. Increase Your Down Payment
    • Lenders view buyers who make larger down payments as less risky, which may qualify you for lower rates.
    • Even a small increase, such as going from 10% to 15%, can make a significant difference in your rate and monthly payment.
  5. Consider Points and Buydowns
    • Discount Points: Paying upfront fees (known as points) can reduce your interest rate. One point typically costs 1% of the loan amount and lowers your rate by 0.25%.
    • Temporary Buydowns: Some lenders offer programs that temporarily reduce your rate in the first few years of the loan, helping with initial affordability.

Special Programs for First-Time Buyers and Low-Income Borrowers

Certain programs can help buyers access better rates, even if their financial profile is less than perfect:

  • FHA Loans: These government-backed loans offer competitive rates and lower credit score requirements.
  • VA Loans: Veterans and active-duty military members may qualify for zero-down-payment loans with favorable rates.
  • USDA Loans: Designed for rural buyers, these loans often include competitive rates and zero-down-payment options.
  • State and Local Programs: Many states offer programs with reduced interest rates for first-time buyers or low-income families.

Common Mistakes That Could Cost You a Better Rate

  1. Not Shopping Around: Accepting the first rate you’re offered can mean missing out on better deals.
  2. Failing to Lock in Your Rate: Rates can rise unexpectedly, so waiting too long to lock could cost you.
  3. Ignoring Closing Costs: A loan with a slightly higher interest rate but lower closing costs may be a better overall deal.
  4. Making Financial Changes Before Closing: Avoid large purchases, job changes, or new credit inquiries before your loan is finalized, as these could affect your rate.

Calculating the Impact of Interest Rates on Your Mortgage

Understanding how even small rate changes affect your monthly payment is vital.

Example Scenario:

  • Loan Amount: $300,000
  • Interest Rate: 5% vs. 6%
  • Loan Term: 30 years

At 5%, your monthly payment (principal and interest) would be approximately $1,610. At 6%, the payment rises to $1,798—an increase of $188 per month and $67,680 over the life of the loan.

This underscores the importance of securing the lowest possible rate.


Final Thoughts: Positioning Yourself for the Best Interest Rate

Securing a competitive interest rate requires preparation, research, and strategic decision-making. By improving your credit, comparing lenders, and exploring options like points or special programs, you can save money and make homeownership more affordable.


Alicia Ewbank, CCS
Windermere Real Estate East, Inc,
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com

Buying • November 29, 2024

Mortgage Pre- Approval

Why Getting Pre-Approved Is Crucial in This Market

Taking the leap into homeownership for the first time can feel overwhelming, but one key step can simplify the journey: getting pre-approved for a mortgage. For first-time homebuyers, understanding this process and why it matters is essential for navigating today’s competitive housing market. Here is the break down!


What Is Mortgage Pre-Approval?

For first-time buyers, pre-approval is like getting a “green light” for your homebuying journey. It’s a formal evaluation by a lender that determines how much they are willing to lend you, based on your financial profile.

Why It’s Important:

  • It gives you clarity on what you can afford.
  • It shows sellers you’re serious and ready to make an offer.
  • It sets you up for success when house hunting by focusing only on homes within your budget.
  • It gives your agents the OK to start showing you homes on the market

Why First-Time Buyers Need Pre-Approval in Today’s Market

  1. Stand Out in a Competitive Market
    As a first-time buyer, you may face competition from more experienced buyers. A pre-approval letter signals to sellers that you’ve done your homework and are financially prepared to purchase, making your offer more attractive.
  2. Avoid Financial Surprises
    Without pre-approval, you might waste time viewing homes outside your price range or discover unexpected challenges when applying for a loan. Pre-approval provides a clear picture of what you can afford.
  3. Gain Confidence in the Process
    For first-time buyers, the homebuying process can feel intimidating. Pre-approval simplifies it by providing concrete numbers, allowing you to focus on finding the right home rather than worrying about finances.

How to Get Pre-Approved: A Guide for First-Time Buyers

  1. Understand Your Financial Situation
    Before applying, take stock of your finances:

    • How much can you comfortably pay for a home each month?
    • Do you have savings for a down payment and closing costs?
    • What is your credit score?

    Many first-time buyers assume they need perfect credit or a 20% down payment, but this isn’t true. Programs like FHA loans often allow for lower credit scores and down payments as small as 3.5%.

  2. Research First-Time Buyer Programs
    Many lenders offer special programs for first-time buyers, such as:

    • Lower interest rates.
    • Down payment assistance.
    • Reduced private mortgage insurance (PMI) requirements.
  3. Gather Your Documents
    First-time buyers should be prepared to provide:

    • Proof of income (pay stubs, W-2s, or 1099s). Ideally 2 years worth.
    • Bank statements to show savings and assets.
    • A list of debts, including student loans, car loans,zdvt h mb bbbb           b credit cards.
  4. Choose the Right Lender
    Look for lenders who specialize in working with first-time buyers. A good lender will explain your options and help you find a loan that fits your needs.
  5. Submit Your Application
    The lender will evaluate your financial information and creditworthiness. Once approved, you’ll receive a pre-approval letter specifying your maximum loan amount, estimated interest rate, and loan terms.

Tips for First-Time Buyers After Pre-Approval

  1. Stay Within Your Budget
    Just because you’re approved for a certain amount doesn’t mean you need to spend it all. Consider your lifestyle and future expenses when deciding on a home price.
  2. Avoid Big Financial Changes
    • Don’t open new credit accounts or take on new debt(retail cards).
    • Avoid large purchases, such as cars or furniture, until after closing.
  3. Keep Saving
    Even after pre-approval, continue saving for unexpected costs like moving expenses, home repairs, or an increased down payment.

Common Questions First-Time Buyers Ask

  1. What’s the Difference Between Pre-Approval and Pre-Qualification?
    Pre-qualification is a preliminary estimate of how much you might borrow.                                                                Pre-approval is a formal process that involves verifying your financial information, making it a stronger indication of your ability to purchase.
  2. How Long Does a Pre-Approval Last?
    Pre-approvals are typically valid for 60-90 days. If your search takes longer, you may need to reapply.
  3. Can I Still Be Denied After Pre-Approval?
    Yes, but this usually happens if your financial situation changes (e.g., taking on new debt or losing your job). That’s why maintaining financial stability is critical.

First-Time Buyer Perks: Special Loan Programs to Explore

As a first-time buyer, you may qualify for programs that make homeownership more affordable:

  • FHA Loans: Lower down payments and credit score requirements.
  • VA Loans: For veterans and active-duty military, with no down payment required.
  • USDA Loans: For buyers in rural areas, offering zero-down-payment options.
  • State and Local Assistance Programs: Many states offer grants or low-interest loans to help with down payments or closing costs.

Final Thoughts: Your First Step to Owning a Home

Getting pre-approved isn’t just a box to check; it’s a foundation for your entire homebuying journey. It empowers you to shop for a home with confidence, knowing your budget and demonstrating to sellers that you’re ready to close the deal.

Are you ready to take the first step toward your dream home? Contact us today to learn more about getting pre-approved and explore programs designed just for first-time buyers. We’re here to guide you every step of the way!”

I you need help finding a lender, look on my website under Buyer & Selling and then click on Seller and Buyer Guides and Lenders

Buying • November 22, 2024

What is a mortgage?

Understanding the Basics of Mortgages

Buying a home is one of the biggest financial decisions most people will ever make, and understanding how mortgages work is essential to navigating this process confidently. Here, we’ll break down the key components of a mortgage, how it functions, and why it’s an important tool for most homebuyers.


What Is a Mortgage?

A mortgage is a loan specifically designed to help individuals purchase real estate. It allows buyers to secure a home without needing to pay the full purchase price upfront. Instead, the buyer makes an initial down payment and agrees to repay the remaining amount, plus interest, over a set period.

  • The Borrower: You, the homebuyer, agree to the terms of the loan and make regular payments.
  • The Lender: A bank, credit union, or mortgage company provides the funds needed to purchase the property.
  • The Collateral: The property itself acts as security for the loan. If the borrower cannot meet the terms of repayment, the lender has the right to foreclose on the property.

Key Mortgage Terms to Know

  1. Principal
    • The amount of money borrowed to purchase the home.
    • Example: If you buy a house for $400,000 and put down $80,000, your loan principal is $320,000.
  2. Interest
    • The cost of borrowing money, expressed as a percentage of the loan.
    • Example: If your loan has a 6% interest rate, this is the annual fee the lender charges based on your remaining loan balance.
  3. Loan Term
    • The time period over which the loan will be repaid. Common terms are 15, 20, or 30 years.
    • A longer term often means smaller monthly payments but more interest paid over time.
  4. Monthly Payment
    • The amount you pay the lender each month, which typically includes:
      • Principal: A portion of the loan balance.
      • Interest: The lender’s fee.
      • Escrow Payments: Taxes and insurance collected by the lender and held until due.
  5. Amortization
    • The process of gradually paying off a loan over time. Early payments go primarily toward interest, while later payments go more toward the principal.

How Mortgages Work: A Basic Overview

  1. Application Process:
    • You apply for a mortgage through a lender by submitting your financial information, including income, credit score, and debt levels.
  2. Loan Approval:
    • The lender evaluates your financial profile and determines whether you qualify for a loan and for how much.
  3. Loan Disbursement:
    • Once approved, the lender provides the funds, which are used to pay the seller for the home.
  4. Repayment:
    • You repay the loan in monthly installments, which include principal, interest, and other associated costs, until the loan is paid off.

Why Mortgages Are Essential

For most buyers, saving enough money to pay for a home outright isn’t feasible. Mortgages make homeownership accessible by breaking the cost into manageable monthly payments. Here are some key reasons why mortgages are beneficial:

  • Affordability: Allows buyers to purchase a home without needing the full amount upfront.
  • Financial Leverage: Home prices often appreciate over time, making a mortgage an investment in an asset likely to increase in value.
  • Tax Benefits: Mortgage interest and property taxes may be deductible on your income taxes, providing financial savings.

Key Takeaways

Understanding the basics of how mortgages work is the first step to making informed decisions about home financing. Knowing the terms, how payments are structured, and why mortgages are a valuable tool can help you approach the process with confidence.