
 Facebook
 X
 Pinterest
 Copy Link
A Season to buy and sell
Which season to buy or sell depends on when you are ready! Washington’s real estate market follows a distinct seasonal rhythm. If you are planning a move, understanding the “Spring Sprint” versus the “Summer Stroll” is the difference between a high-stress bidding war and a relaxed, successful negotiation. If you miss both of these markets you are still in the running for the “Holiday Sprint.” Just don’t forget your rain boots and Coffee!
Here is the breakdown of why the calendar month matters just as much as the house itself.
The Early Spring “Sprint” (February – Early April)
In the Pacific Northwest, the real estate market “wakes up” much earlier than the flowers. By February, the “New Year, New Home” energy is in full swing. Is this the right season to buy or sell for you?
The Environment:
-
The “First-to-Market” Surge: Buyers who sat out the holidays hit the market with intensity.
-
Multiple Offer Situations: Because inventory is still building from winter lows, demand often outpaces supply. It is common to see multiple offers on well-priced homes during this window.
Pros & Cons:
Fresh Inventory: You get first dibs on the newest homes of the year. | High Competition: You will likely be competing with other “hungry” buyers.
Optimism: Appraisals are often supported by rising spring data. | Pressure: You may have to waive contingencies to win.
Beat the Heat: You close and move before the peak summer temperatures. | Higher Prices: Scarcity often drives sale prices above the listing price.
The Summer “Stroll” (June – September)
As soon as school lets out and the “Big Dark” is replaced by 9:00 PM sunsets, the market undergoes a significant shift. While many assume summer is the busiest time, it is actually the most balanced. Let’s take a look and see if this might be the right season to buy or sell.
The Environment:
-
The “Vacation Effect”: Many buyers pause their search for family trips, weddings, and graduations.
-
Inventory Catch-up: Homes that didn’t sell in the spring “rush” are still active, and summer listings are still trickling in. This creates a higher Months of Supply, giving you more leverage.
Pros & Cons:
Power: Sellers with homes still on the market by July are often motivated to deal. | “Pick-over” Inventory: Some homes may be “stale” listings with underlying issues.
Contingencies are Back: It is much easier to include home inspections and seller credits. | Heat & Logistics: Moving in 90-degree Washington heat can be a challenge.
Better Visibility: You can see how the AC handles the heat and how the yard truly looks. | Dwindling Options: New listings start to slow down as we head into late August.
The “Holiday Hustle” (Late October – Late December)
This sixty-day window is primarily defined by firm deadlines. Specifically, whether it involves a tax year-end or a job relocation starting January 1st, participants in this market are rarely just “browsing.” Consequently, most buyers and sellers active during this time are moving with a clear mission in mind. Does any of this strike a cord with your circumstances? Maybe this might be the season to buy or sell for you. Furthermore, the desire to be “home for the holidays” creates a unique sense of urgency that you won’t find in the spring.
For Buyers: The Gift of Leverage
Historically, anyone listing a home this time of year is motivated and ready to close.
- The “Motivated Seller” Factor: Anyone listing their home in November or December usually has to sell. They might be relocating for work, settling an estate, or need to close before the tax year resets. This puts you in a position of power.
-
Tax Advantages: Closing before December 31st can provide significant immediate benefits. In 2026, with the One Big Beautiful Bill Act (OBBBA) provisions in full effect, you may be able to deduct mortgage interest, property taxes, and loan points on the tax return you file just a few months later.
-
The “Vibe Check”: Winter is the most honest time to see a house. You’ll know exactly how the furnace sounds, if the gutters actually drain, and how cozy the living room feels when it’s 4:30 PM and dark outside.
For Sellers: The “Serious Only” Crowd
From a seller’s perspective, the weather and timing play a huge factor.
-
Zero “Looky-Loos”: Nobody tours a home in a December rainstorm just for fun. If a buyer is at your door in late fall, they are pre-approved and ready to sign.
-
Stunning Presentation: Pacific Northwest homes look incredibly inviting when decorated for the holidays. Between the twinkling lights and the cozy hearths, your home’s “emotional appeal” is at an all-time high.
-
Inventory Scarcity: While many neighbors wait until the spring to list, your home stands out as one of the few high-quality options available. This can lead to a surprisingly quick and clean sale despite the season.
Spring/Summer vs. Fall/Winter: At a Glance
| Season | Market Vibe | Best For… |
| Early Spring (Feb-Apr) | High Energy / Competitive | Variety & Selection (but expect bidding wars) |
| Summer (Jun-Sept) | Relaxed / Balanced | Negotiating repairs & choosing with less pressure |
| Late Fall/Winter (Oct-Dec) | Deadline Driven / Strategic | Fast closings, serious buyers, and tax benefits |
The Bottom Line
In 2026, we are seeing 6.1%–6.3% mortgage rates stabilize. This means the “panic” of 2024 and 2025 is gone. Whether you buy in the busy spring or the relaxed summer, you are entering a “Decision Mode” market rather than a “Reaction Mode” market.
Which Season is Right for You?
-
Choose Early Spring if: You have a very specific “must-have” list and want the absolute widest selection of high-quality homes, and you have the stomach (and the budget) for a fast-paced negotiation.
-
Choose Summer if: You are looking for a “deal,” want more time to make a decision, and want to keep your inspection and financing contingencies firmly in place.
- Choose Fall/Winter if: You have a deadline, looking to take advantage of the tax incentives or are noticing you need more or less space in your life.
As your specialist, my job is to help you win in April’s heat, negotiate a credit in August’s sun or fight for your timeline in the winter blues.
Not sure what market to take advantage of, or ready to take the plunge, call for a risk free consultation.
Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com
Summer in the Pacific Northwest
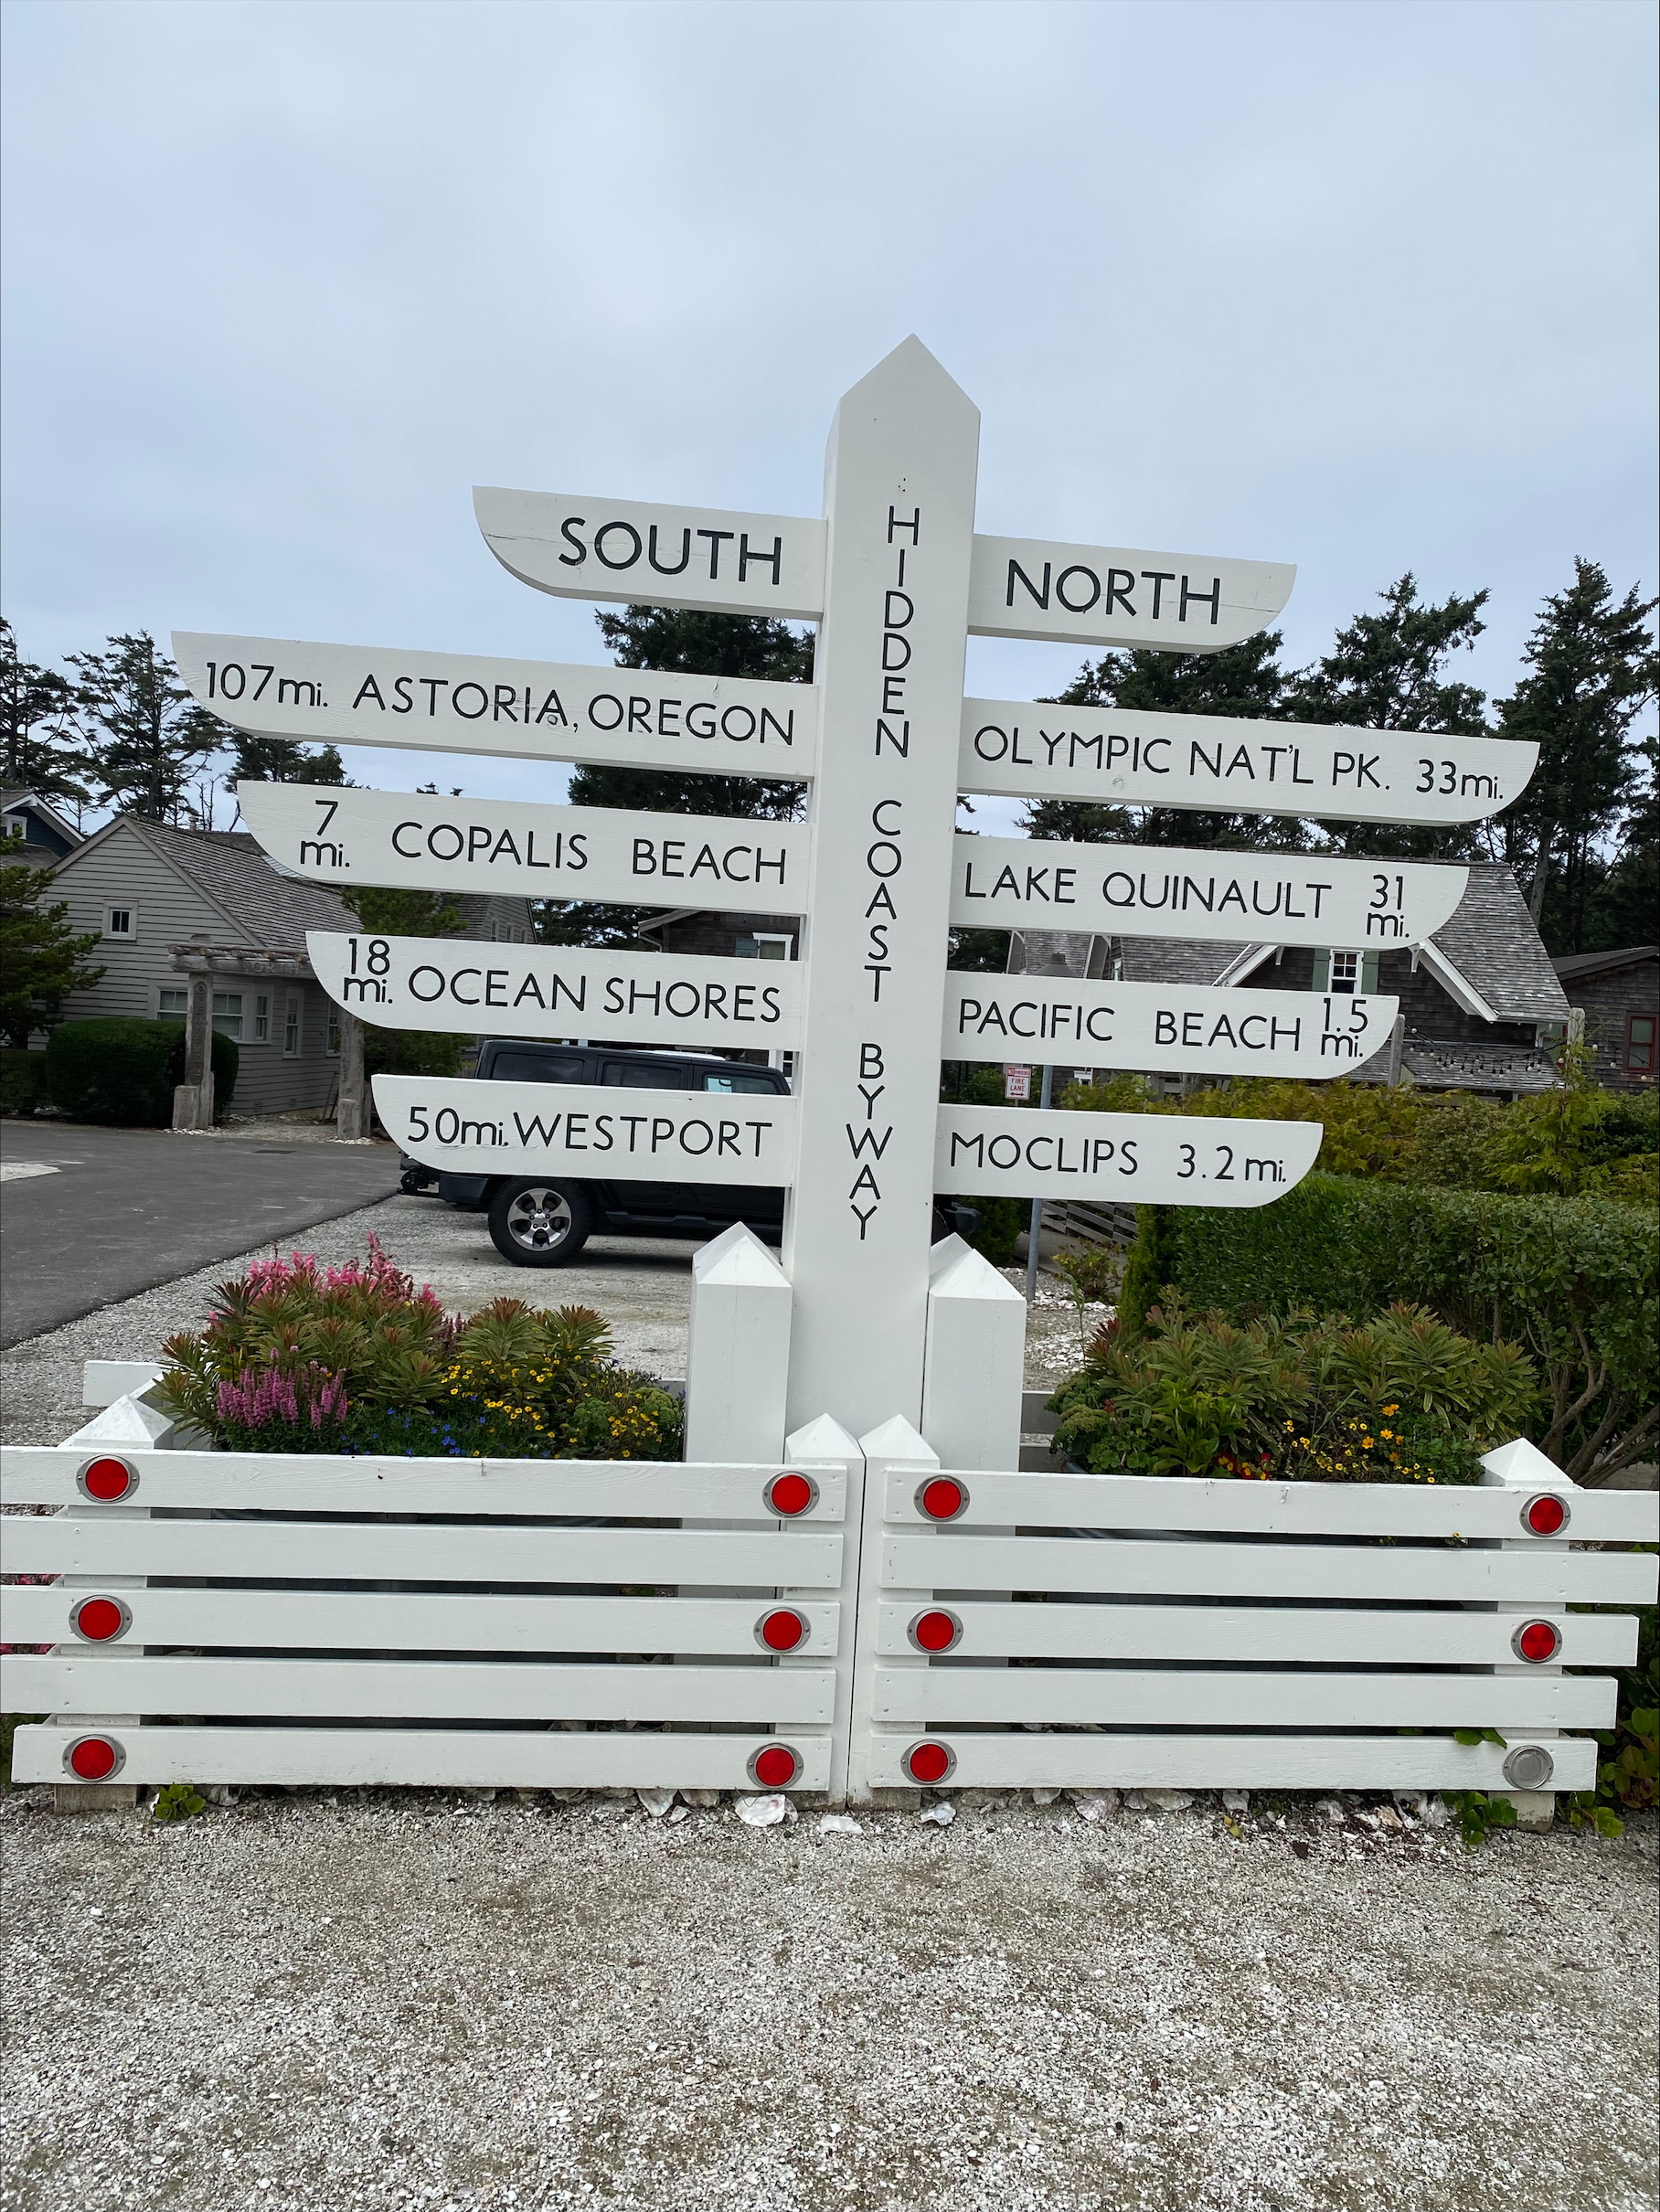
Summer in the Pacific Northwest (July & August) aren’t just months; they are a reward for the long, misty winters. This is the “Golden Window” when the alpine snow finally melts, the Salish Sea turns a deep cerulean, and the “Big Dark” is a distant memory.
If you’re looking to make the most of summer 2026, here is your roadmap to the ultimate Pacific Northwest adventure. In addition, if you are thinking of taking a trip out to the ocean, Seabrook Washington is a wonderful destination on the beautiful 101 highway Reach out to me for an extra 20% off your stay there, courtesy of myself and our partnership between Windrermere and Seabrook.
1. The High Country: Mountains & Hiking
By mid-July, the high-altitude trails in the North Cascades and Mount Rainier National Park are finally accessible.
-
The Enchantments: For the serious hiker, July and August are peak “Larch” and wildflower season. Even if you don’t have a coveted overnight permit, day-hiking to Colchuck Lake offers some of the most dramatic glacial views in North America.
-
Skyline Trail (Mount Rainier): This 5.5-mile loop at Paradise is at its prime in August. You’ll be hiking through meadows so thick with purple lupine and red Indian paintbrush that it feels like a cinematic set piece.
-
Galbraith Mountain: For mountain bikers, Bellingham’s Galbraith Mountain is a world-class destination. With over 65 miles of single track ranging from beginner-friendly flow to technical downhill, it’s the heart of PNW bike culture.
2. Island Time: Orcas & Boating
The waters of the San Juan Islands are one of the few places on Earth where you can witness Orcas in their natural habitat with near-certainty.
-
Whale Watching: August is prime time for spotting both “Southern Residents” (salmon eaters) and “Bigg’s” (transient) Orcas. Tours departing from Friday Harbor or Anacortes offer naturalist-led excursions.
-
Boating & Kayaking: Rent a kayak in Roche Harbor or Eastsound. The water is calmest in late summer, allowing you to paddle alongside harbor seals and bald eagles. If you have your own boat, “island hopping” to Jones Island or Stuart Island for a night of marine-state-park camping is a summer rite of passage.
3. Small Town Charm & Coastal Escapes
The PNW is defined by its quirky, walkable small towns that feel frozen in time.
-
Leavenworth: This Bavarian-themed village in the Cascades is a summer hub for river tubing down the Wenatchee River and outdoor theater.
-
Port Townsend: Located on the tip of the Olympic Peninsula, this Victorian seaport is a dream for history buffs and sailors alike. Spend an afternoon at Fort Worden (where An Officer and a Gentleman was filmed) or browse the independent bookstores downtown.
- Seabrook: a vibrant, award-winning coastal community perched on a scenic bluff overlooking the Pacific Ocean.Founded in 2004 on the principles of New Urbanism, every detail of this town—from the cedar-shingled cottages to the oyster-shell pathways—is designed for walkability, connection, and a timeless coastal aesthetic.
-
Cannon Beach (Oregon): A few hours south, the iconic Haystack Rock stands guard over one of the most beautiful coastlines in the world. August mornings are often misty, but by noon, the beach is the perfect place for a bonfire.
4. Road Trips & Scenic Rails
Sometimes the best part of the PNW is the journey between the destinations.
-
The Olympic Loop: A 300-mile circuit around the Olympic Peninsula. In July, you can experience the mossy silence of the Hoh Rainforest and the rugged, driftwood-strewn beaches of La Push in a single weekend.
-
Amtrak Cascades: For a car-free adventure, take the train from Seattle to Vancouver, B.C., or down to Portland. The tracks hug the coastline of the Puget Sound, providing views of the water you simply can’t get from the I-5.
-
Oregon Coast Scenic Railroad: For a touch of nostalgia, ride the historic steam locomotive between Garibaldi and Rockaway Beach. It’s a slow, beautiful crawl along the Tillamook Coast that feels like 1926 instead of 2026.
All of these adventures you can partake in during our summer in the Pacific Northwest show you the beauty of what we call home. If you are visiting these areas and thinking of making a move, remember that summer is our best weather!
Planning a beach trip? As a Seabrook Certified Pro and local Real Estate Agent, I can offer you 20% off your next stay! 🏠 Whether it’s your first time visiting or your tenth, I’m here to help with town tips and exclusive savings. Call or email me to grab your discount code!
Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com
Summer Home Maintenance Guide
Here is your 2026 Summer Home Maintenance Guide to keep your property cool, safe, and value-packed.
As we move through 2026, the Pacific Northwest summer is no longer just about enjoying the sun—it’s about preparing for higher heat and protecting your home’s equity. With my 12 years of experience in the Seattle Eastside market, I’ve seen how a few simple summer tasks can save homeowners thousands in long-term repairs.
1. The HVAC “Deep Breath”
Our summers are getting hotter, and your AC or heat pump is now an essential asset.
-
Filter Swap: Replace your HVAC filters every 30–60 days during the summer. This improves air quality and prevents the system from “choking” during a heatwave.
-
Clear the Perimeter: Ensure there is at least 2 feet of clearance around your outdoor condenser unit. Remove any overgrown shrubs, grass clippings, or debris that could restrict airflow.
-
The “Test Run”: Don’t wait for the first 90-degree day. Turn your AC on now to ensure it’s actually blowing cold air. If you hear grinding or rattling, call a pro before their summer schedule fills up.
2. Exterior “Curb Appeal” & Protection
The summer sun and spring rains can take a toll on your home’s shell.
-
Deck Health Check: Sprinkle water on your wooden deck. If it beads up, you’re protected. If it sinks in, it’s time to reseal. Check for loose nails or rotting boards—safety first for those summer BBQs!
-
Window & Door Seals: Inspect the caulking and weatherstripping. Sealing gaps now keeps the cool air inside and lowers your energy bills.
-
Gutter Audit: Even after the spring rains, gutters can fill with “pollen sludge” and debris. Clear them out now to ensure summer thunderstorms don’t cause foundation washouts.
3. Smart Summer Landscaping
In 2026, “Water-Smart” is the new gold standard for Pacific Northwest yards.
-
Mulch Generously: Adding 2–3 inches of organic mulch to your garden beds acts as insulation, keeping the soil cool and moisture locked in.
-
Water Strategically: Water in the early morning or late evening to minimize evaporation. Aim for deep, infrequent soaking rather than daily “spritzing” to encourage deep root growth.
-
The “Defensible Space”: If you live near wooded areas (like Issaquah or Duvall), trim back dead branches and clear dry brush at least 10 feet away from your home to reduce fire risk.
4. Internal Safety Audit
-
Smoke & CO Detectors: Summer is the perfect time to test all alarms and swap out batteries.
-
Ceiling Fan Pivot: Switch your ceiling fans to run counter-clockwise. This pushes cool air straight down, creating a wind-chill effect that allows you to raise your thermostat by a few degrees.
-
Dryer Vent Cleaning: Built-up lint is a leading cause of house fires. Disconnect the vent and vacuum it out to keep your dryer running efficiently and safely.
The Specialist Perspective: Why Maintenance Matters for 2026 Value
In the current more Neutral market During these months, buyers are becoming more selective. When I represent a seller, a home that has a documented history of seasonal maintenance—clean HVAC records, a well-sealed exterior, and healthy landscaping—always commands a higher price and shorter closing time.
If you’re planning to buy or sell this summer, don’t forget Compliance and maintenance go hand-in-hand to protect your home’s legacy.
Contact me today to get started
Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com
Eastside Summer Guide: The Best of Bellevue, Kirkland, and Beyond
What’s happening on the Eastside for the summer?
1. Life on the Water: Lake Washington & Lake Sammamish
Eastside Summers revolves around the lakes. As the weather warms up in May, the waterfront becomes the community’s living room.
Juanita Beach Paddleboarding
-
Kirkland Waterfront: Marina Park is the place to be. You can rent a powerboat or electric boat for a sunset cruise, or simply grab a gelato and walk the promenade. Juanita Beach has a playground, Paddle boarding and kayak rentals and the best Sandy Beach to lounge during our warmer days.
-
Enatai Beach Park (Bellevue): This is a hidden gem for kayakers. You can rent a paddle board and glide through the Mercer Slough Nature Park, where you’ll feel miles away from the city in a lush, wildlife-rich wetland.
-
Lake Sammamish State Park: Ideal for a full day out. With two expansive swimming beaches (Tibbetts and Sunset) and a massive new playground, it’s the premier spot for a summer BBQ.
2. Festival Season: Art, Wine, and Music
The Eastside knows how to throw a summer party. Mark these on your 2026 calendar:
-

Redmond Urban Market
Bellevue Arts Museum (BAM) ARTSfair (July): One of the largest and most prestigious open-air arts festivals in the Northwest. Over 300 artists take over the streets around Bellevue Square.
-
Kirkland Uncorked (July): A waterfront wine festival at Marina Park featuring Washington’s best vintages, food trucks, and a “Bark-testant” dog show.
-
Sammamish Commons Concerts: Pack a picnic and a blanket for free outdoor concerts on the hill—one of the best views of the sunset on the Eastside.
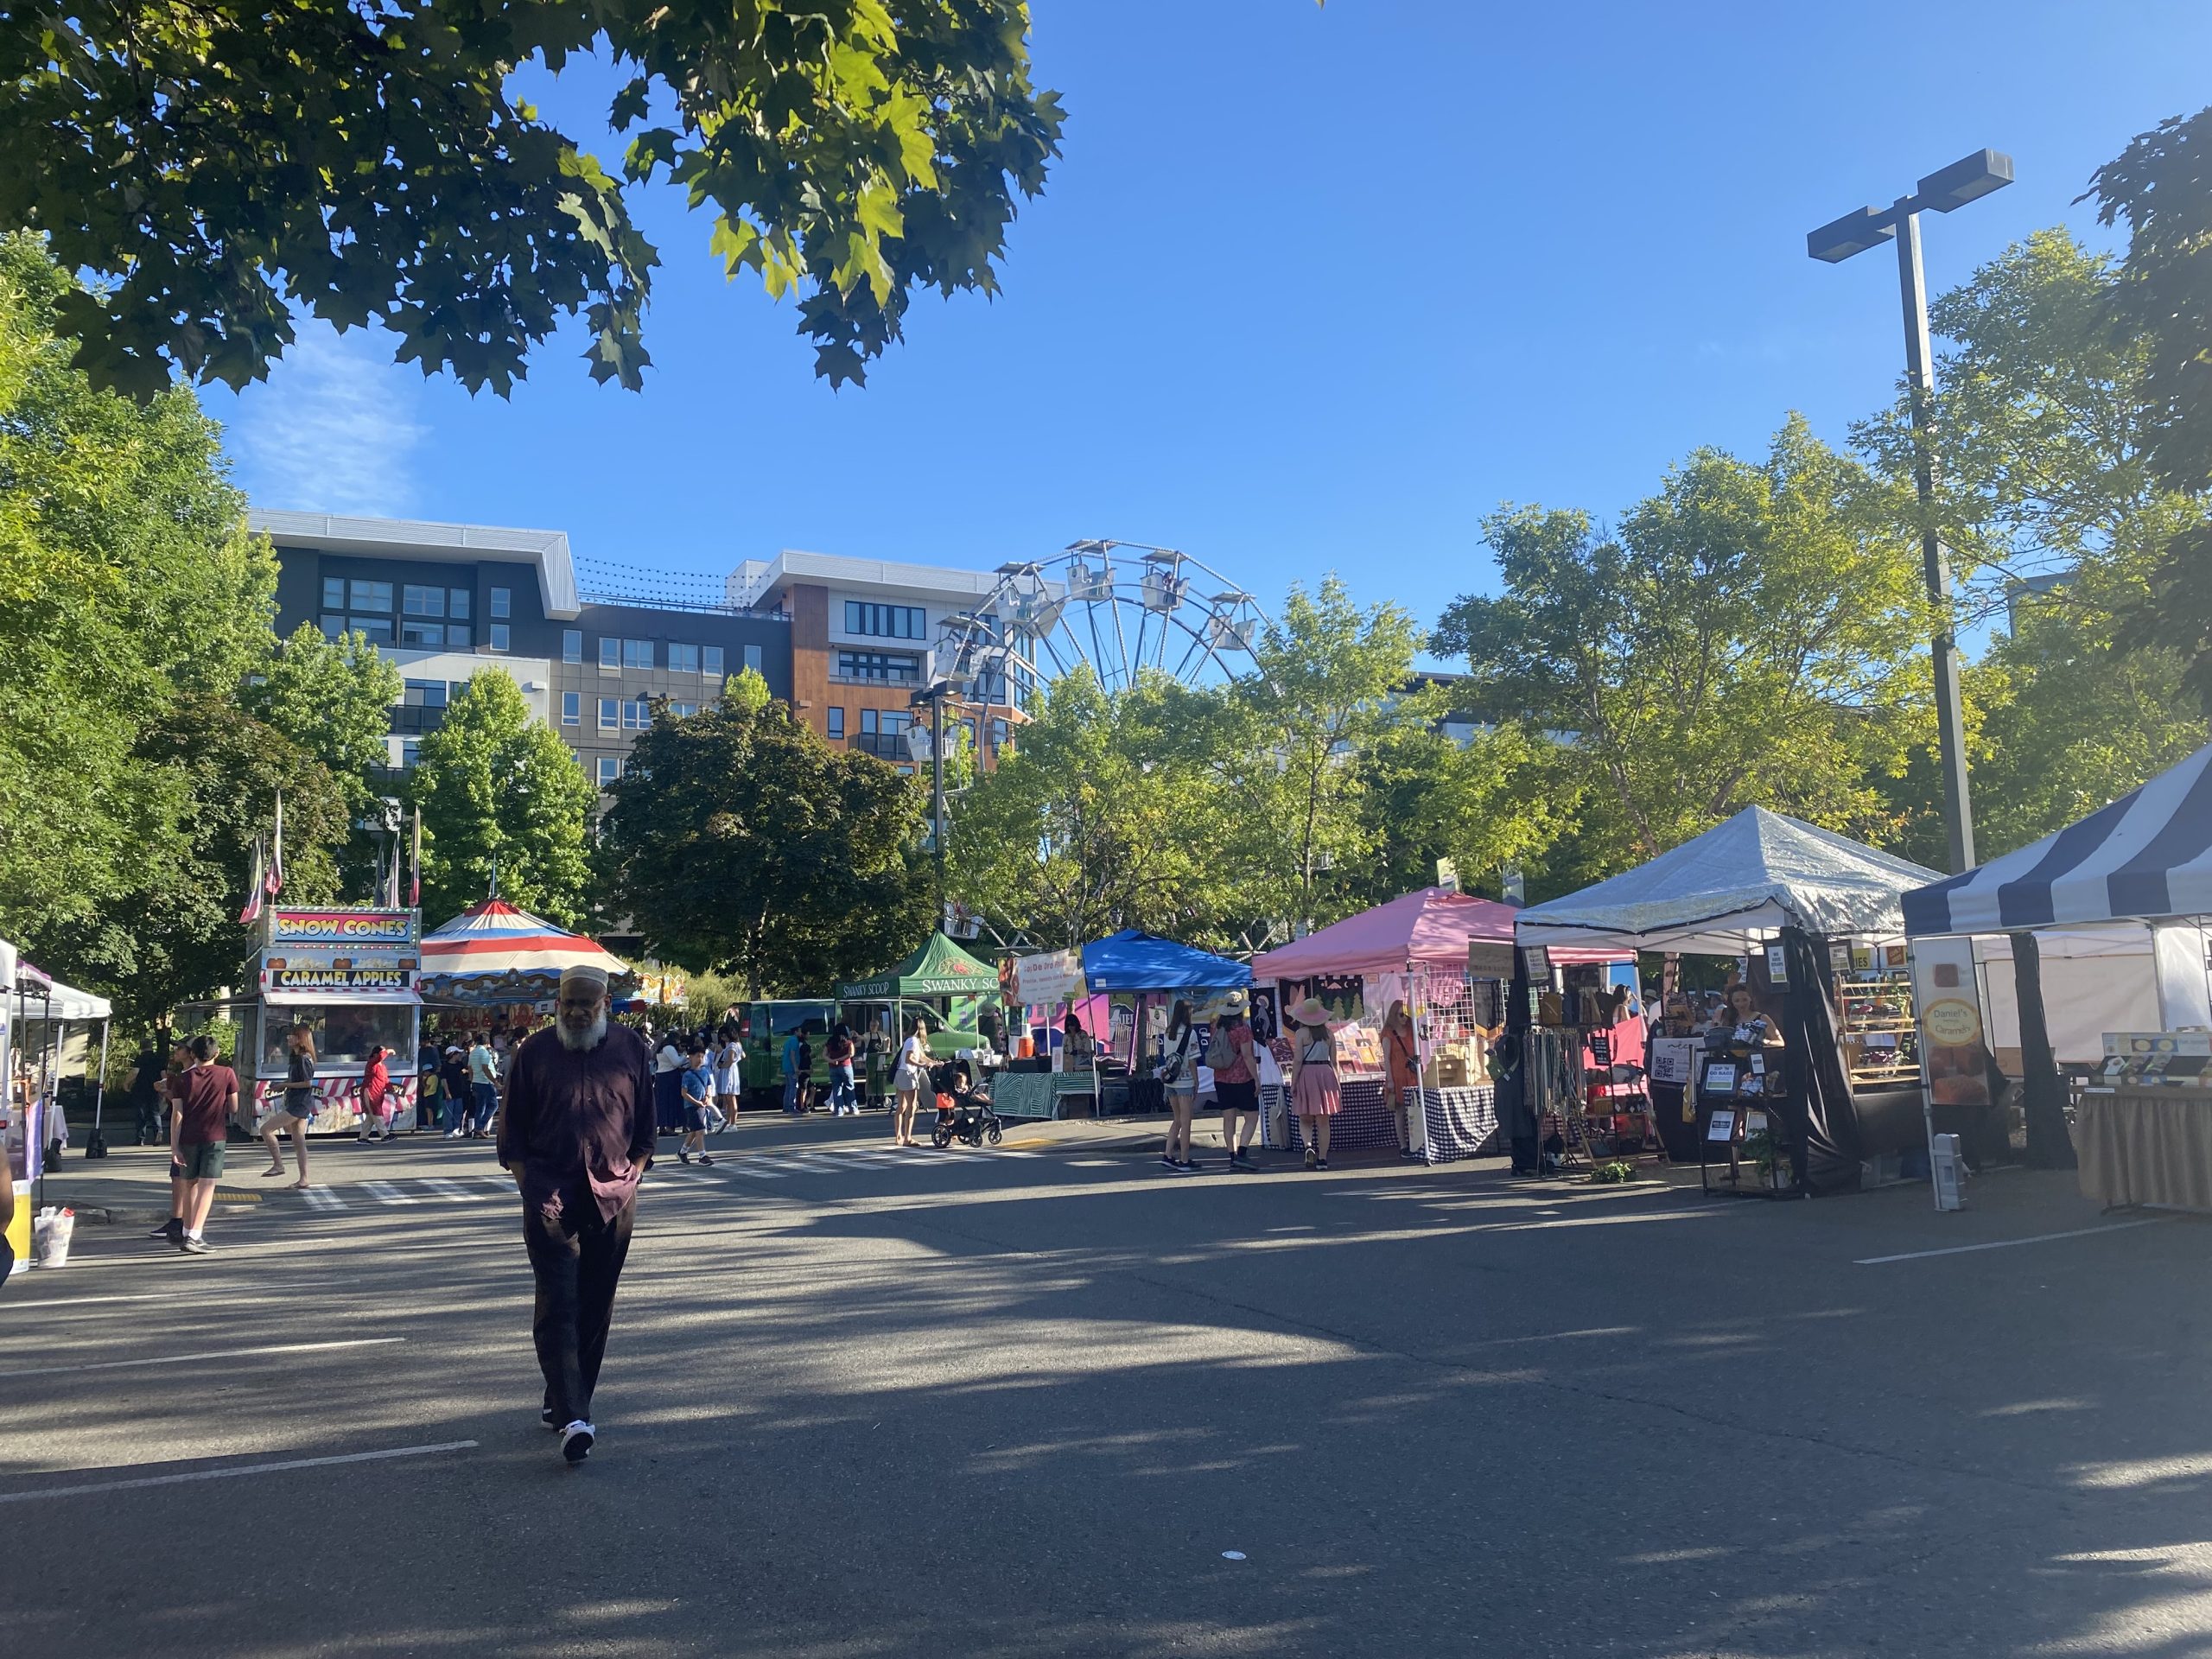
3. Farm-to-Table & Al Fresco Dining
The Eastside’s culinary scene shines when the patios open up.
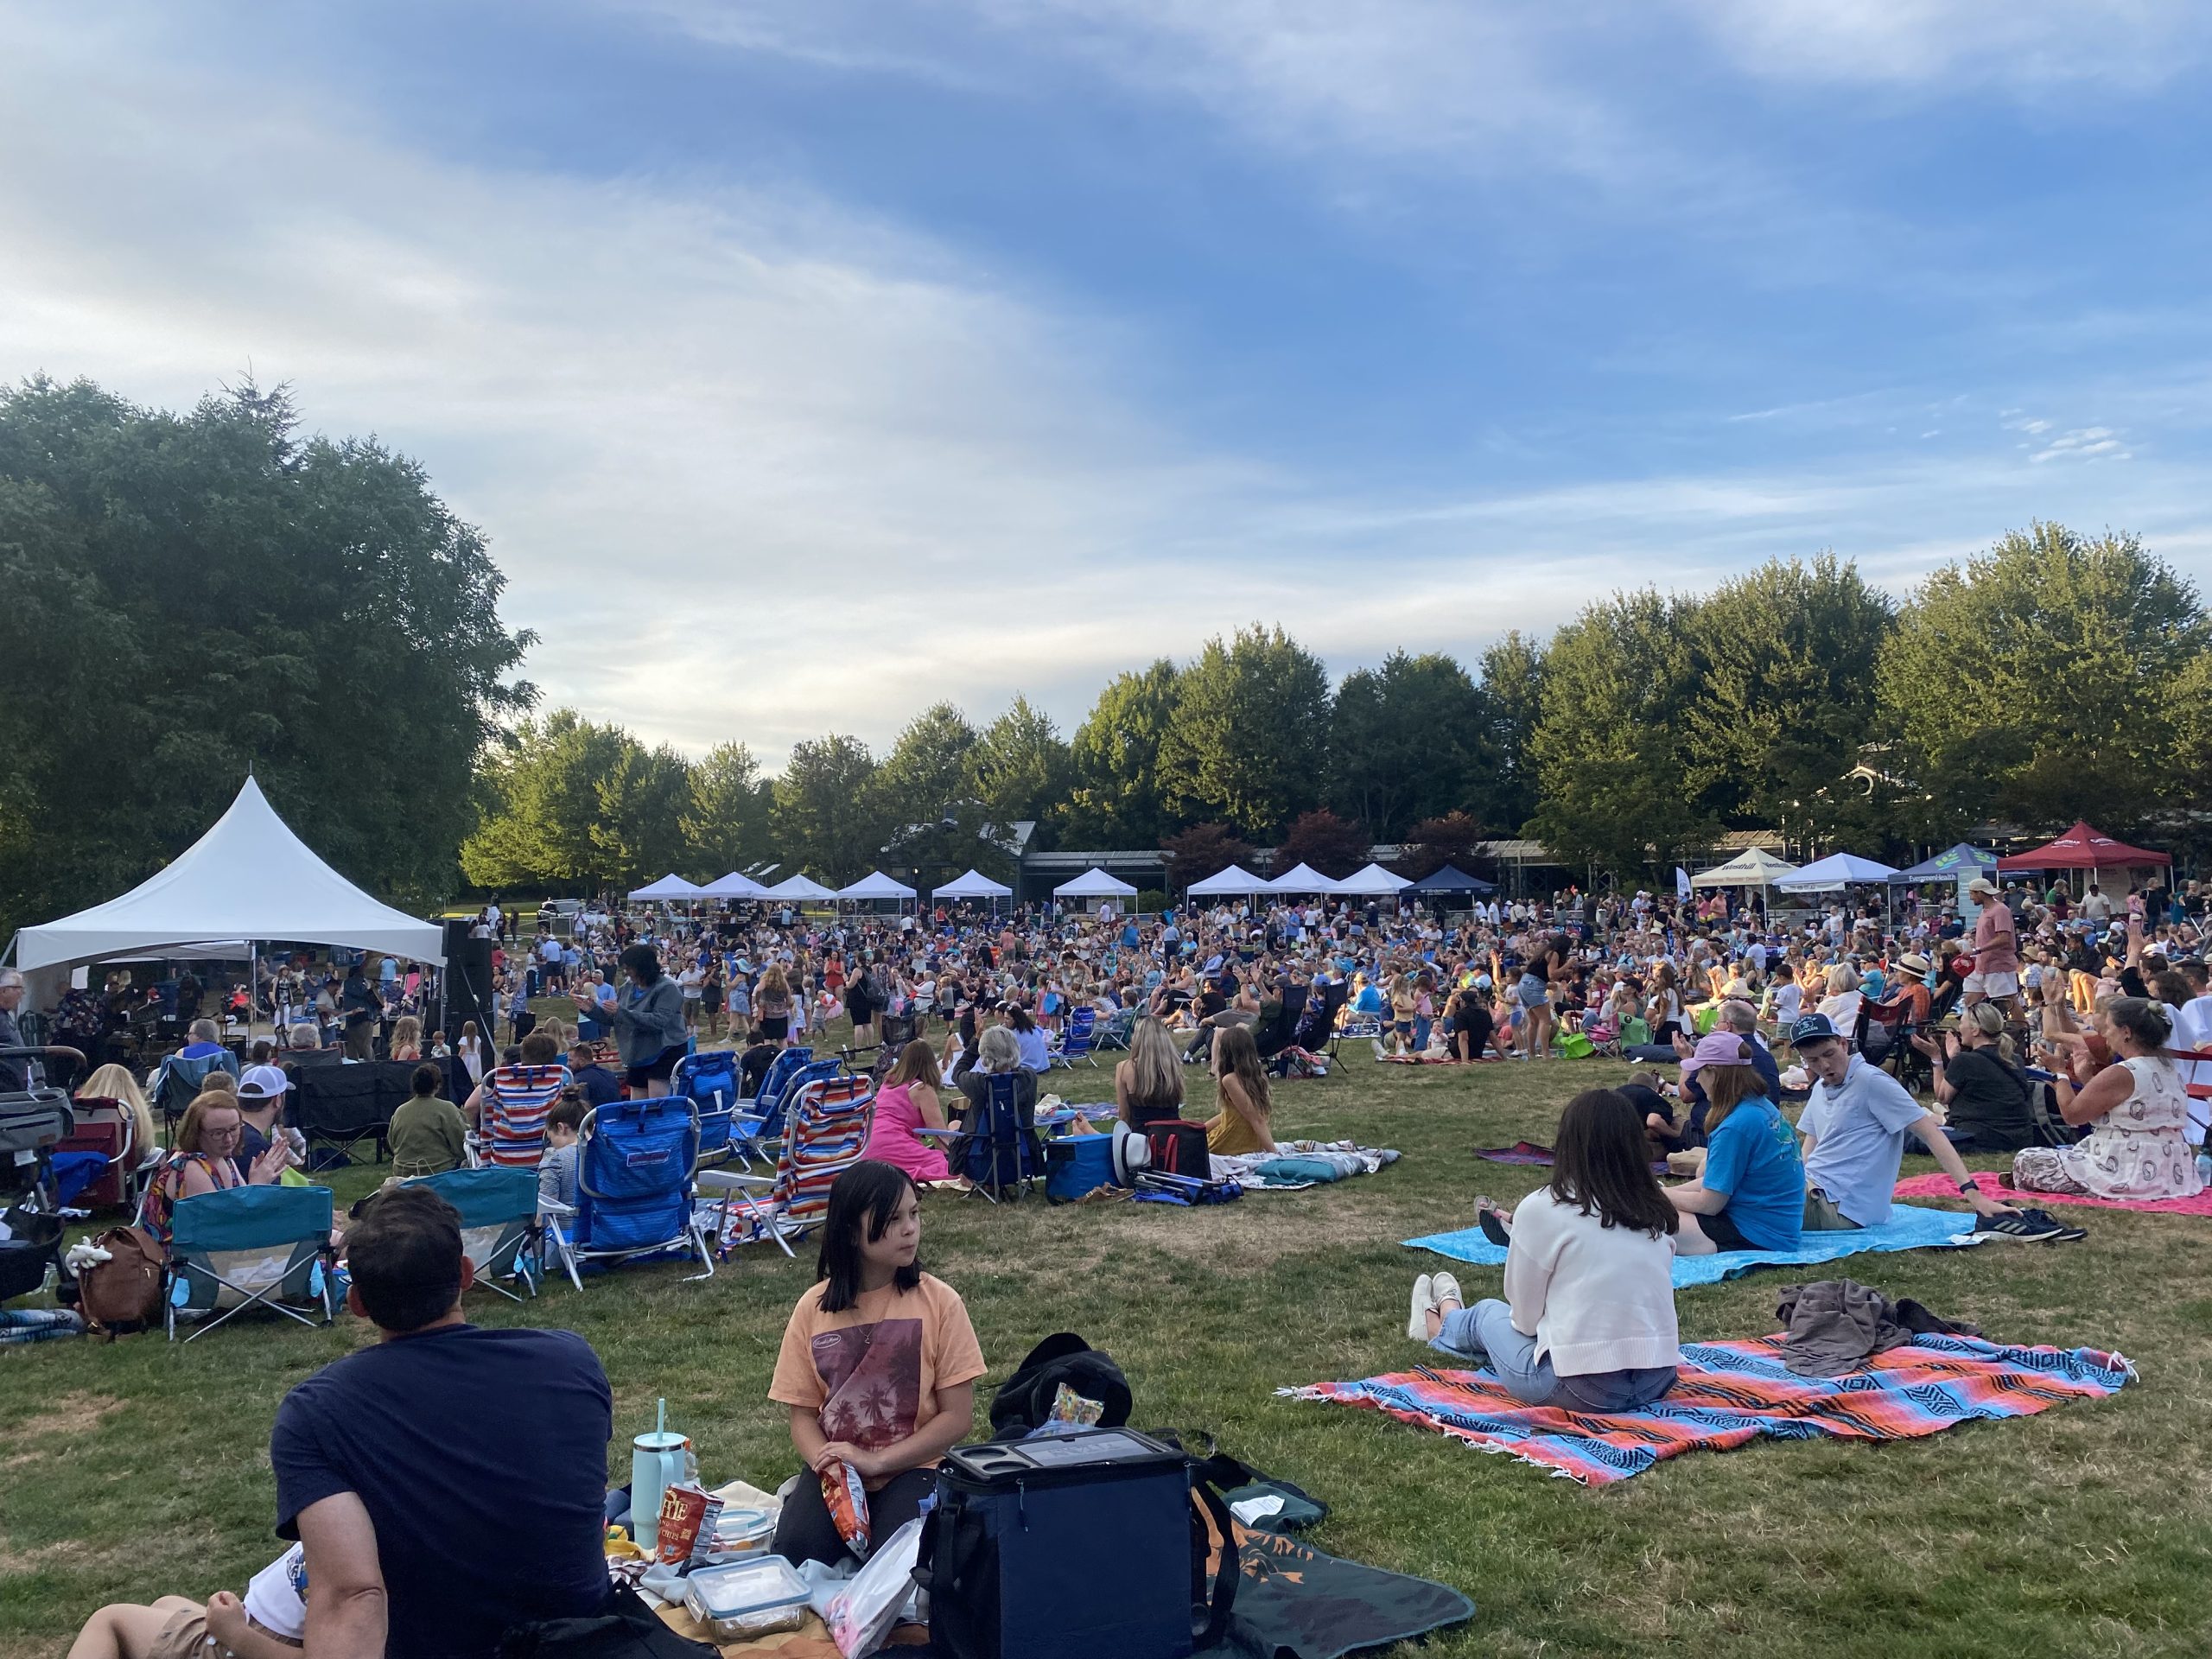
Wilmot Gateway Park, Woodinville
-
Woodinville Wine Country: Just north of Kirkland and 5 minutes off of 405, Woodinville is home to over 130 wineries. In the summer, the lawns at Chateau Ste. Michelle host world-class outdoor concerts. You can also walk along wine alley and stop at boutique shops and restaurants. Bring the whole family to their Summer Concert Series at the slough. Enjoy food, drinks, games and lots of good music each week in July.
-
The Farmers Markets: * Bellevue (Thursdays): Great for a post-work organic haul.
-
Kirkland Wednesday Market: Located right on the water at Marina Park.
-
-
Remlinger Farms (Carnation): A short drive east, this is a summer rite of passage for families. U-pick berries, a steam train, and a farm-themed fun park.
4. Hiking & The Great Outdoors
You don’t have to drive to the Cascades for a great hike.
-
Cougar Mountain Regional Wildland Park: Over 35 miles of trails right in Bellevue/Issaquah. In the summer, the shade of the forest canopy keeps these trails perfectly cool.
-
Bridle Trails State Park: A 482-acre oasis of old-growth forest between Kirkland and Bellevue, perfect for a peaceful walk or horseback riding.
Why Summer is the Best Time to Explore Your New Neighborhood
If you are considering buying a home on the Eastside, there is no better time than the summer to “test drive” the lifestyle.
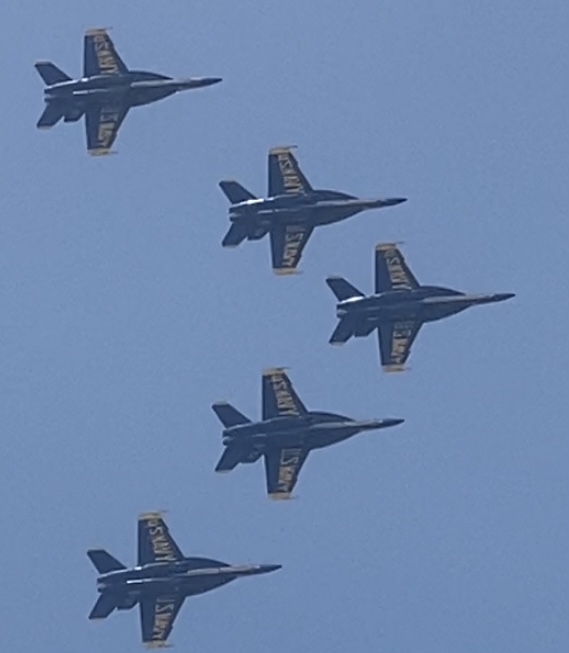
Blue Angles
-
See the “Real” Neighborhood: Walk the streets in the evening to see how active the parks are and how the community interacts.
-
Evaluate the Amenities: Visit the local pools, tennis courts, and HOA-managed beaches while they are in full use.
-
The Specialist Edge: As an Eastside resident and local agent of over 12 years, I don’t just know the houses; I know which streets have the best 4th of July block parties and which buildings have the best rooftop views for the Seafair Blue Angels (or join me to view the Blue angles in person at the Museum of Flight in Renton).
Thinking of buying or selling this summer? Reach out today so I can help you start planning your next move.
Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com
Summer might be the best time to buy!
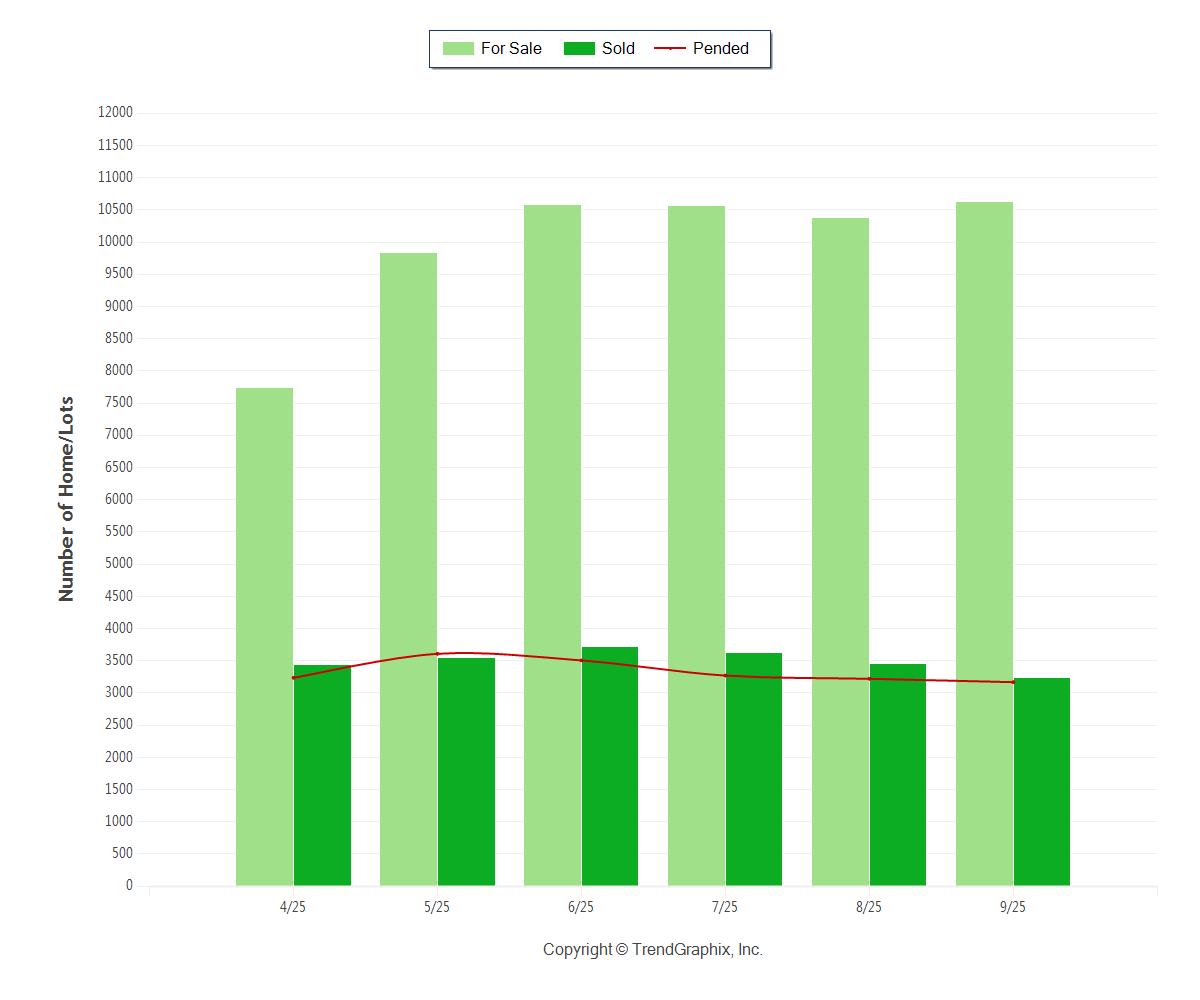
The “Summer Divergence”: Why Buyers Slow Down While Choice Stays High
When we start out, one thing we think about is: When is the best time to buy a house in King & Snohomish County? When looking at the actual market data, we see a fascinating trend: while the “frenzy” of buyers often cools down late-spring, the number of homes available for you to choose from remains remarkably steady. This is what I call the Summer Opportunity Gap.
1. The Supply Stays, but the “Sold” Sprints Slow Down
According to the latest TrendGraphix metrics, we are seeing a significant 33.2% drop in Sold properties month-over-month as we move out of the initial spring rush. However, the For Sale inventory is actually increasing by 4.2%. So, When is the best time to buy a house in King & Snohomish County?
-
The Interpretation: The “For Sale” line (the options you have) is climbing, while the “Sold” line (your competition taking homes off the market) is dipping. For the first time in months, supply is outpacing the immediate demand.
2. Moving from a “Seller’s Sprint” to a “Neutral Market”
The report officially classifies the current market as “Neutral.” This is a huge shift from the “Seller’s Market” of previous years.
-
The Benefit to You: In a neutral market, you have Time. You aren’t forced to waive inspections or make a decision in 4 hours. With more “For Sale” inventory staying on the market longer, you have the leverage to negotiate.
3. The “Pended” Reality Check
While “Pending” sales (homes going under contract) show a seasonal uptick of 46% as buyers re-enter the market in spring, they are still down 20.1% from six months ago. * What this means: There is a “ceiling” on the competition. Even though more people are looking than in the dead of winter, the overall volume of competing buyers is significantly lower than the historical peaks.
I‘ve seen this cycle repeat itself for over a decade. The ‘smart money’ moves when the Sold line dips but the Inventory line stays green. That is exactly what we see during the summer months (April to August). If you find yourself asking, When is the best time to buy? and your not looking to be in a rush and not have to deal with multiple offers on a property, this might be the best time for you to start.
Call me today to set you up for success!
Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com
Certified Condo Specialists: Avoid WUCIOA Liabilities
Why You Need a Certified Condo Specialist in 2026
Buying into a Common Interest Community (CIC) in 2026 is an exciting milestone. However, the legal fine print has never been more complex. While Washington state is moving toward a unified law called WUCIOA, many older buildings are currently “out of compliance.” Specifically, several associations have struggled to meet the new mandates that went into effect on January 1st. Which is where you need to make sure your agent is a Certified Condo Specialist, not just a local agent or what some call themselves “condo specialist.” Don’t take an agent’s word for it, ask them for their certification. If they don’t have the above image on any of their business cards or paperwork or the letters CCS after their name, then you will know that they have not been certified by the Council of Condominium Specialists® and the Council of CID Specialists®.
The “Hidden” Special Assessment Risk
Furthermore, WUCIOA now requires much stricter financial transparency. This includes new rules for how reserve funds are held and invested. Consequently, if you buy into a building with an outdated Reserve Study, you face a major risk. You might be walking into a massive Special Assessment that the current owners haven’t disclosed. Therefore, auditing the building’s financial health is no longer optional; it is essential and a Certified Condo Specialist knows how to help you read through the reports.
Your New 2026 Rights
In addition to financial shifts, your personal rights as a homeowner have expanded. Did you know that as a buyer in 2026, you have a statutory right to install an EV Charger or a Heat Pump? Under the new law, a Board cannot “unreasonably” deny these requests. Nevertheless, many buildings still have “blanket bans” in their old bylaws. Since these rules are often unenforceable relics, you need an agent who can spot the difference. Simply put, you need a Certified Condo Specialist (CCS).
The CCS Advantage for Buyers
While most agents focus on the kitchen, I focus on RCW 64.90 compliance. As your specialist, I decode the “Resale Certificate” to find hidden red flags. For example, I look for these key indicators:
-
Are the reserves held in a proper interest-bearing account?
-
Has the Board followed the 2026 open-meeting notice requirements?
-
Is there a clear 24-month repayment plan for any borrowed funds?
Ultimately, my goal is to protect you from a legal headache. I ensure your new home is a sound investment in this new era of real estate.
2026 questions for reviewing HOA Docs
Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com
Seasonal Maintenance
Seasonal maintenance is important. Maintaining a home is about protecting your investment and preventing small issues from becoming “emergency-priced” repairs. Since its March, many homeowners are shifting focus from winter safety to spring preparation.
Here is a comprehensive, 50-task checklist categorized by frequency and system to keep your property in peak condition.
Monthly “Quick Hits” Maintenance (12 Tasks)
These should be done on the first of every month to keep systems running efficiently.
-
Change HVAC Filters: Check and replace (30–90 days depending on pets/allergies).
-
Clean Garbage Disposal: Run ice cubes and baking soda to sharpen blades and deodorize.
-
Clean Range Hood Filters: Use a degreaser to remove grease buildup from cooking.
-
Test Smoke & CO Detectors: Use the “test” button; replace the unit if it’s over 10 years old.
-
Inspect Fire Extinguishers: Ensure the gauge is in the green and the pin is intact.
-
Check for Leaks: Look under kitchen and bathroom sinks for moisture or “verdigris” on pipes.
-
Clean Aerators: Unscrew faucet tips and soak in vinegar to remove mineral scale.
-
Inspect Exterior Drainage: Ensure water isn’t pooling near the foundation after rain.
-
Flush Unused Drains: Run water in guest showers/sinks to keep P-traps full and block sewer gas.
-
Test GFCI Outlets: Press “test” and “reset” on outlets in wet areas (kitchen/bath).
-
Check Water Softener: Add salt if the level is low.
-
Monitor Utility Bills: A sudden spike in water usage often signals a hidden pipe leak.
Quarterly “Deep Dives” Maintenance (8 Tasks)
Tackle these every three months (Jan, April, July, Oct).
13. Test Garage Door Auto-Reverse: Place a 2×4 in the path to ensure the door reverses upon contact.
14. Inspect Window/Door Seals: Check for drafts or cracked caulking; replace to lower energy bills.
15. Run Dishwasher Cleaner: Use a specialized tablet or vinegar to clear food debris from the pump.
16. Vacuum Refrigerator Coils: Dust buildup here makes the compressor work 15% harder.
17. Test Sump Pump: Pour water into the pit to ensure the pump triggers and drains.
18. Inspect Attic: Look for signs of pests (droppings) or roof leaks (water stains on rafters).
19. Check Electrical Cords: Inspect for fraying or heat marks near outlets.
20. Deep Clean High-Traffic Floors: Steam clean carpets or deep-scrub tile grout.
The “Big Two” Seasonal Overhauls of Maintenance (20 Tasks)
Focus on these during the transition into Spring (now) and Fall.
Spring Preparation (March–May)
21. Inspect Roof: Use binoculars to look for missing shingles or damaged flashing.
22. Clean Gutters & Downspouts: Remove winter debris to prevent foundation washouts.
23. HVAC Professional Tune-up: Schedule your A/C service before the summer heat hits.
24. Pressure Wash Siding: Remove mold, algae, and winter grime.
25. Inspect Siding & Trim: Look for rot or “bubbling” paint that indicates moisture.
26. Service Lawn Equipment: Sharpen mower blades and change the oil.
27. Turn on Outdoor Water: Reactivate hose bibs and check for winter burst pipes.
28. Fertilize & Aerate Lawn: Prep the soil for peak growing season.
29. Repair Driveway Cracks: Fill asphalt or concrete cracks to prevent weed growth.
30. Clean Window Screens: Remove dust and pollen to allow for fresh air.
Fall Winterization Maintenance (Sept–Nov)
31. Furnace Inspection: Ensure your heating system is safe and efficient for winter.
32. Sweep Chimney: Have a pro clean the flue if you use a wood-burning fireplace.
33. Drain/Store Hoses: Disconnect from spigots to prevent pipes from freezing.
34. Insulate Pipes: Wrap exposed pipes in unheated areas (garage/crawlspace).
35. Mulch Flower Beds: Protect roots from the first frost.
36. Check Weatherstripping: Seal the “envelope” of your home to keep heat in.
37. Clean Dryer Vent: Remove lint from the entire length of the duct to prevent fires.
38. Rake Leaves: Prevent them from matting down and killing your lawn.
39. Clean Outdoor Furniture: Store or cover to prevent winter rot.
40. Reverse Ceiling Fans: Set to clockwise (low speed) to push warm air down.
Annual “Longevity” Tasks (10 Tasks)
These extend the life of your home’s most expensive components.
41. Drain Water Heater: Flush out sediment to improve efficiency and prevent tank “popping.”
42. Inspect Main Sewer Line: Consider a camera inspection if you have older trees/pipes.
43. Termite/Pest Inspection: Have a pro check for wood-destroying organisms.
44. Check Foundation for Cracks: Look for “step cracks” in brick or vertical cracks in concrete.
45. Lubricate Moving Parts: Oil garage door rollers, hinges, and sliding door tracks.
46. Sanitize Washing Machine: Run a hot cycle with bleach or cleaner to remove mold/smells.
47. Check Bathroom Grout/Caulk: Recaulk tubs and showers to prevent wall-cavity rot.
48. Inspect Deck for Safety: Look for loose boards, rusted hangers, or wobbly railings.
49. Flush Septic Tank: If applicable, inspect every year and pump every 3–5 years.
50. Update Home Inventory: Take photos/videos of your belongings for insurance purposes.
Printer friendly: HOME MAINTENANCE CHECKLIST
Alicia Ewbank, CCS
Windermere Real Estate East, Inc.
aliciae@windermere.com
(206)446-1952
aliciaewbank.withwre.com


